
Auto Insurance Discounts Oregon: Ways to Save on Your Policy
Oregon drivers overpay for auto insurance every single day. Most people stick with their current policy without realizing they’re leaving hundreds of dollars on the table each year.
At ISU Insurance Solutions Group, we’ve helped countless Oregonians find auto insurance discounts that actually work. This guide shows you the real savings available and how to claim them.
Auto Insurance Discounts That Actually Lower Your Oregon Premium
Oregon drivers leave hundreds of dollars on the table every year by claiming only a fraction of available discounts. The gap between potential savings and actual savings comes down to knowing which discounts move the needle and which ones barely register on your premium.
Safe Driving Records Pay Real Money
A clean driving record matters far more than most people realize. Drivers without accidents or violations qualify for safe driver discounts that typically reduce premiums by 10 to 25 percent depending on your insurer. One infraction wipes out your discount entirely, which means a single ticket or minor accident can cost you hundreds over three years.
Stacking Discounts Creates Serious Savings
The real savings come from combining discounts on top of each other. When you stack a safe driver discount with multi-policy bundling, you hit reductions of 30 to 40 percent in many cases. Bundling your auto policy with homeowners or renters coverage works because insurers want to keep all your business under one roof-this typically saves between 15 and 25 percent on auto alone, according to industry data.
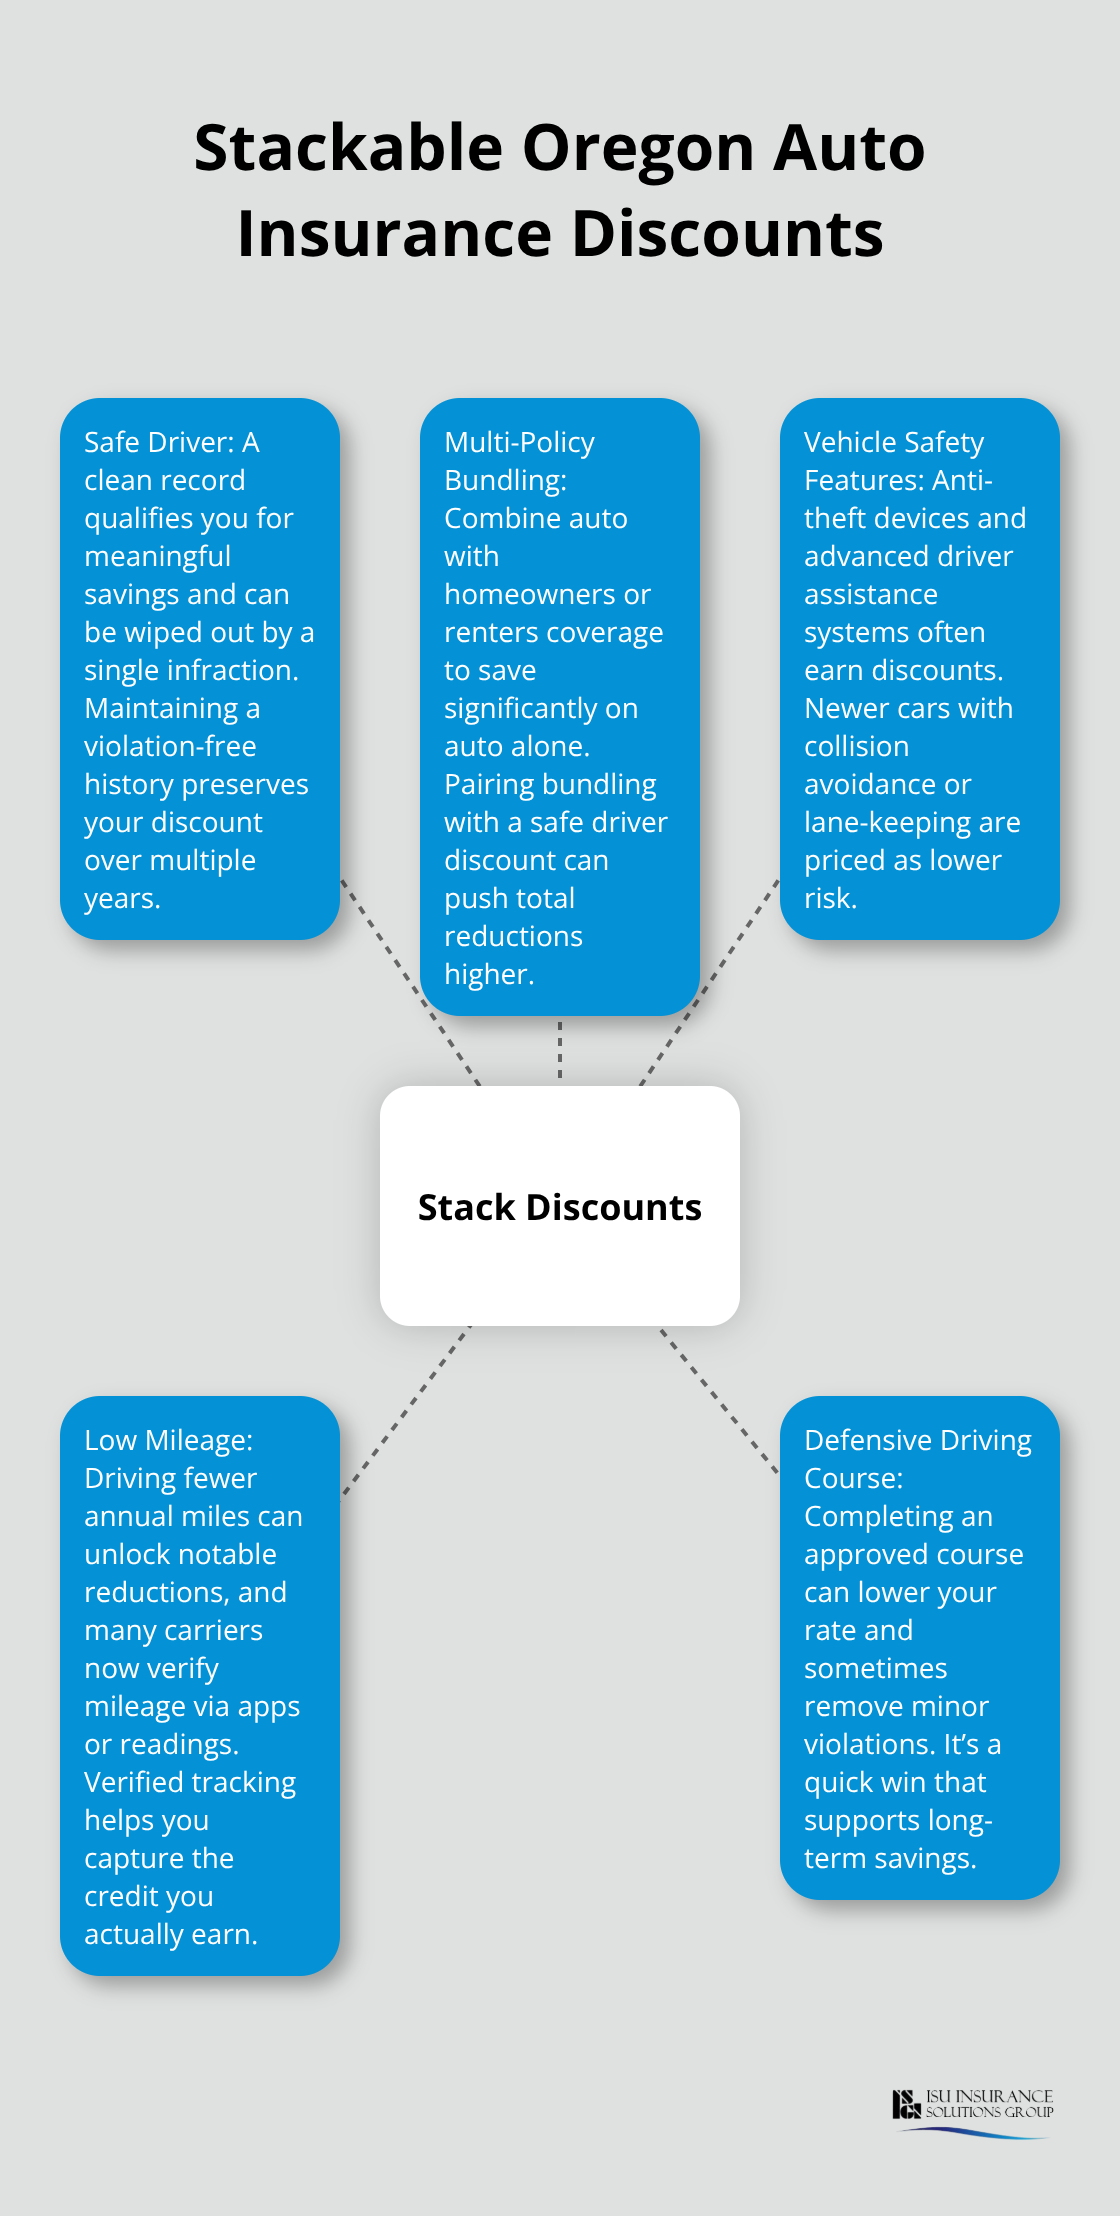
Vehicle safety features represent another meaningful category. Cars equipped with anti-theft devices, automatic seatbelts, or advanced driver assistance systems qualify for discounts ranging from 5 to 15 percent. Newer vehicles with collision avoidance or lane-keeping assist get viewed as lower risk and priced accordingly.
Uncover Hidden Discounts Through Direct Contact
Contact your current insurer and request a complete list of discounts you qualify for versus those you already receive. Many people miss 5 to 10 percent in available savings simply because they never asked. Insurance companies don’t advertise every discount equally, and some require you to actively opt in.
Certain professions like education, healthcare, or military service qualify for occupational discounts that save 10 to 15 percent. Low-mileage discounts apply if you drive fewer than 7,500 to 10,000 miles annually (a change that became more common after remote work shifts). Completing an approved defensive driving course can lower your rate by 5 to 10 percent and sometimes waive minor traffic violations from your record.
Update Your Policy When Life Changes
Annual policy reviews catch discounts you may have missed or that apply now but didn’t before. Installing anti-theft devices, improving your credit score, or reducing your annual mileage should trigger lower premiums. Contact your insurer directly when your life circumstances change rather than waiting for them to notify you of new discounts.
These discount strategies form the foundation of smart savings, but finding the absolute best rates in Oregon requires comparing options across multiple carriers and understanding how different agents approach your coverage needs.
How to Lower Your Premium Without Cutting Coverage
Raise Your Deductible Strategically
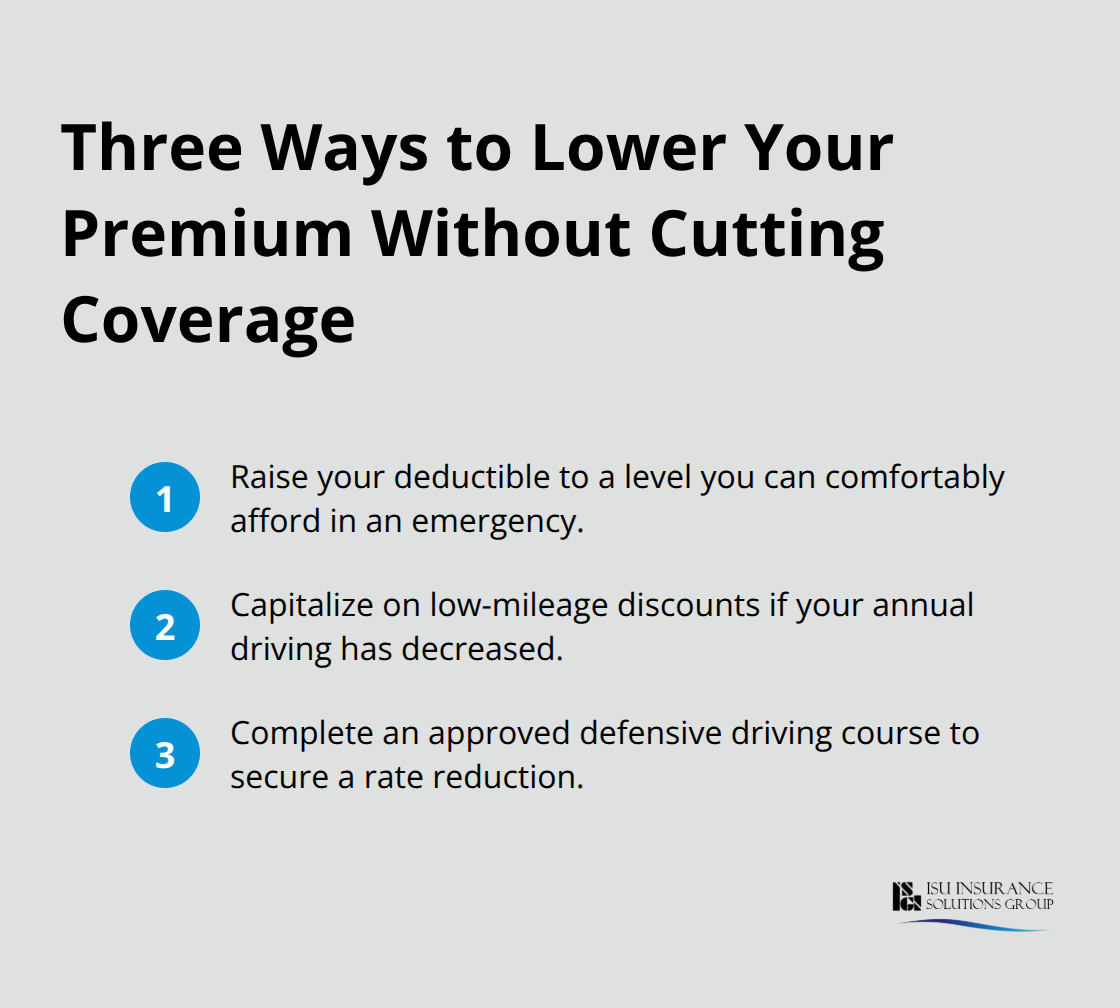
Increasing your deductible stands as one of the fastest ways to cut your auto insurance costs in Oregon, but most drivers approach this decision wrong. Raising your deductible from $500 to $1,000 typically saves 15 to 30 percent on your collision and comprehensive coverage, according to insurance industry data. You accept more financial responsibility in an accident, which means the insurer takes on less risk. However, only raise your deductible to an amount you can actually pay out of pocket without financial strain. A $2,500 deductible saves money until you hit a pothole and owe that amount immediately. The real strategy involves matching your deductible to your emergency fund, not chasing the lowest premium possible.
Capitalize on Low-Mileage Discounts
Low-mileage discounts represent untapped savings for remote workers and people who’ve shifted their commute patterns. If you drive fewer than 7,500 miles annually, most Oregon insurers offer reductions ranging from 10 to 25 percent depending on your carrier. Some companies now use mobile apps or odometer readings to verify your actual mileage rather than relying on your estimate, which means you get credited only for miles you genuinely drive. This shift toward verified tracking has made low-mileage discounts more accessible and accurate than ever before.
Complete a Defensive Driving Course
Defensive driving courses provide a direct path to lower rates without changing your coverage. Completing an approved course qualifies you for a 5 to 10 percent discount with most insurers and can remove minor traffic violations from your driving record. Many courses cost between $20 and $50 online and take just a few hours, making the return on investment substantial over a three-year policy period. Oregon’s Driver and Motor Vehicle Services program offers approved options that meet insurer requirements.
These strategies work individually, but combining them with the discount opportunities from the previous section creates even stronger savings. The next step involves comparing how different Oregon carriers apply these reductions to your specific situation.
Finding Your Best Rate in Oregon
Compare Quotes Across Multiple Carriers
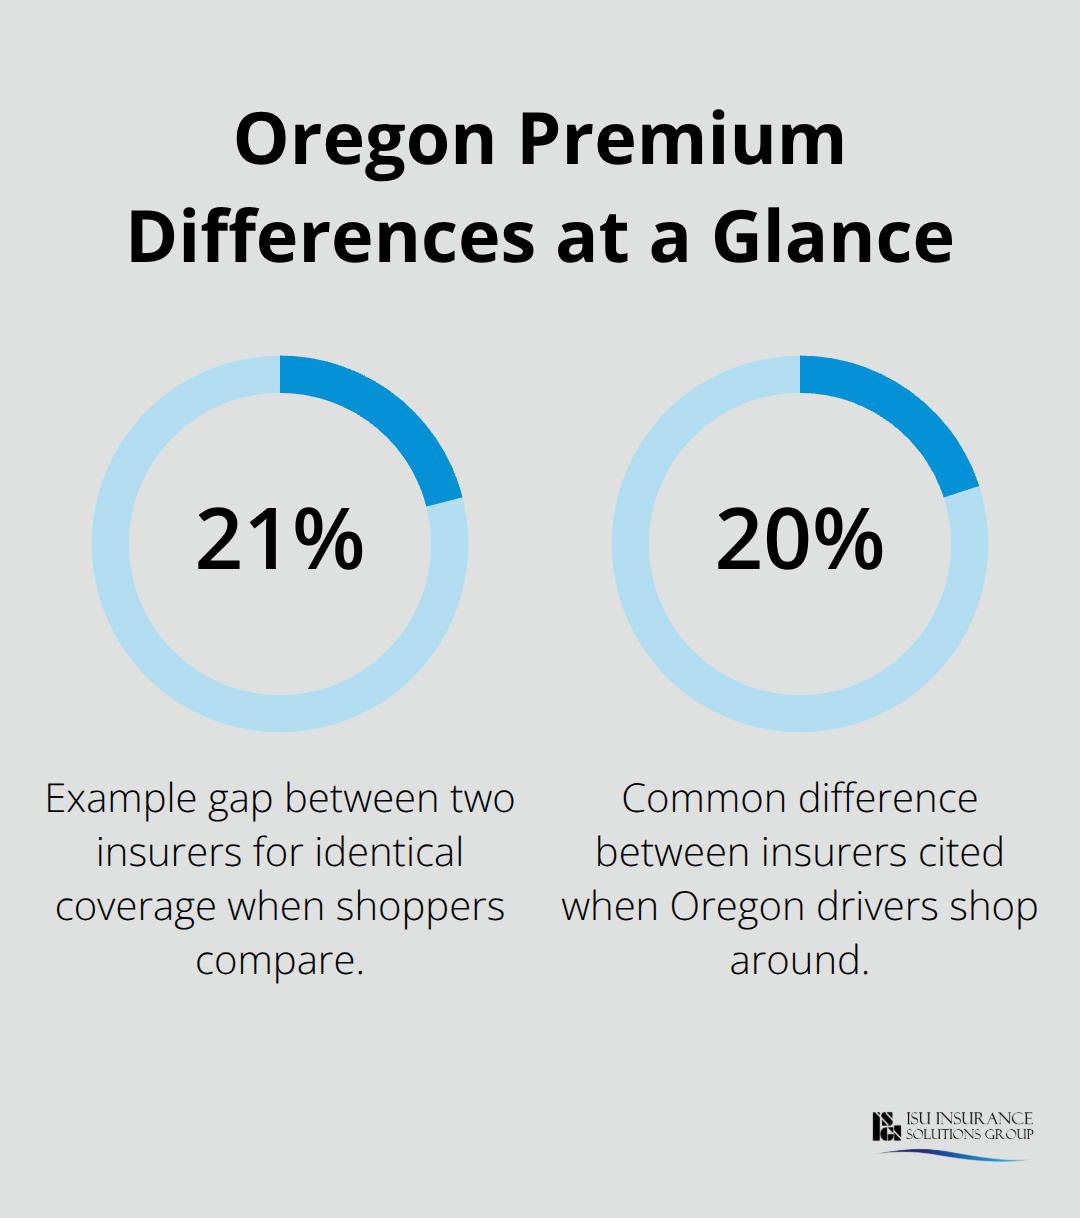
Comparing quotes across multiple carriers reveals how dramatically premiums vary for identical coverage. A driver with a clean record might pay $1,200 annually with one insurer and $950 with another for the same policy-that’s a 21 percent difference for absolutely nothing except shopping around. Most Oregon drivers accept their renewal rate without checking alternatives, which means they leave hundreds of dollars on the table. Getting quotes from at least three carriers takes roughly 20 minutes online and shows you exactly where your current insurer stands against the competition.
State Farm, Geico, Progressive, and regional carriers all price risk differently based on their underwriting models and risk appetite. One insurer might heavily reward defensive driving course completion while another barely credits it. Another might offer aggressive low-mileage discounts while a competitor ignores remote work patterns entirely. The only way to know which carrier aligns with your specific situation involves pulling actual quotes rather than guessing based on advertisements.
Work with an Independent Agent
An independent agent accesses multiple carriers simultaneously rather than locking you into one company’s offerings. An independent agent representing 20 or more carriers runs your information through different underwriting systems and shows you side-by-side comparisons without you submitting repetitive applications. This approach saves time and reveals options that online quote tools miss because agents understand local Oregon factors like weather patterns affecting comprehensive claims or regional accident statistics.
Independent agents also negotiate with carriers on your behalf and advocate for better rates based on your profile. They catch discounts and coverage gaps that automated systems overlook. One call generates multi-carrier quotes so you see your options immediately instead of hunting through websites individually.
Review Your Policy Annually
Annual policy reviews matter more than most people realize because your circumstances change constantly. A promotion raising your income might qualify you for new discounts. Installing a home security system could lower your homeowners premium and trigger bundling savings on auto. Paying off a vehicle removes collision coverage needs and cuts costs significantly. Moving to a safer neighborhood or reducing commute miles shifts your risk profile downward.
Contacting your agent or insurer once yearly translates these changes into lower premiums rather than leaving them hidden in your policy. Many people assume their agent will proactively notify them, but that rarely happens-you must initiate the conversation to capture savings that apply to your updated situation. Your life changes faster than your insurance policy adjusts on its own.
Final Thoughts
Oregon drivers who stack safe driver discounts with bundled policies and vehicle safety features capture savings that reach 40 to 50 percent in many cases. Your current policy likely contains unclaimed discounts worth hundreds of dollars annually. Contact your insurer and request a complete list of available reductions versus what you’re actually receiving to identify the gap between potential and actual savings.
Comparing quotes across multiple carriers reveals how dramatically premiums vary for identical coverage, with 20 percent differences between insurers being common. Annual policy reviews catch new auto insurance discounts Oregon that apply to your updated circumstances, whether that’s a job change, reduced commute, or life event that shifts your risk profile. Shopping around pays immediate dividends and accelerates your path to lower rates.
We at ISU Insurance Solutions Group help Oregon drivers find auto insurance discounts that actually reduce their premiums through independent agent access to multiple carriers. One call generates multi-carrier quotes tailored to your specific situation, revealing savings you won’t find shopping alone. Contact us to review your current coverage and capture the discounts you’re missing.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.





