
Car Insurance Discounts Oregon: Save More with Bundles and Safe Driving
Oregon drivers overpay for car insurance every single year. Most people stick with whatever rate they got when they first signed up, missing out on substantial savings that are sitting right there.
We at ISU Insurance Solutions Group know that car insurance discounts in Oregon fall into three main categories: bundling policies together, maintaining a clean driving record, and using telematics devices that monitor your actual driving habits. This blog post walks you through exactly how to stack these discounts and lower your premium.
Which Oregon Car Insurance Discounts Actually Save You Money
Multi-Policy Bundling Delivers the Biggest Savings
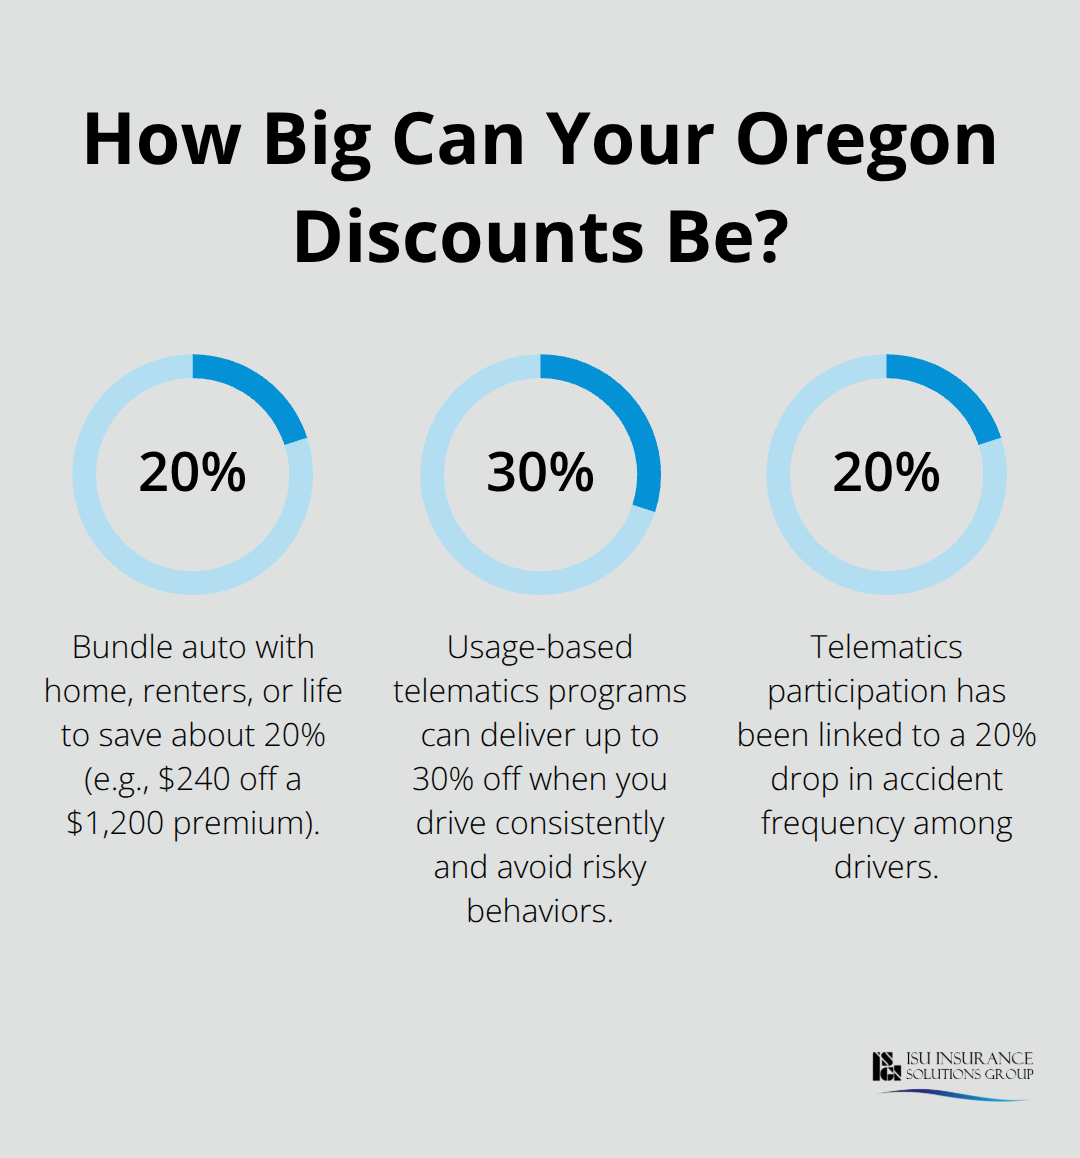
Bundling multiple policies remains the single most effective way to reduce your car insurance costs in Oregon. When you combine auto insurance with home, renters, or life coverage under one carrier, insurers typically offer bundling discounts. Some carriers offer even steeper reductions for customers who stack three or more policies together. The math is straightforward: if you’re paying $1,200 annually for car insurance, a 20 percent bundle discount saves you $240 per year without changing your coverage.
Most Oregon drivers miss this opportunity because they never ask their current provider about available discounts or they assume switching carriers is too complicated. One phone call to compare multi-carrier quotes can uncover significant savings. We at ISU Insurance Solutions Group work with over 20 carriers, which means we can show you exactly which combinations produce the best rates for your specific situation.
Safe Driver Discounts Reward Your Clean Record
Safe driver discounts operate on a simple principle: carriers reward you for not causing accidents or receiving traffic violations. Oregon drivers with a clean driving record for three to five years typically qualify for discounts ranging from 10 to 30 percent, depending on the insurer. Low mileage discounts apply if you drive fewer than 7,500 miles annually, which qualifies you for reductions between 5 and 15 percent since you spend less time on the road.
Usage-Based Programs Track Your Actual Driving Habits
Usage-based insurance programs work differently than traditional discounts. You install a monitoring device or app that tracks your actual driving behavior, and the system rewards safe habits like smooth acceleration, consistent speeds, and minimal nighttime driving. These programs can produce discounts up to 30 percent if you demonstrate responsible driving patterns. Telematics devices have reduced claim frequency among participants.
Stack Multiple Discounts for Maximum Savings
Oregon’s competitive insurance market means you shouldn’t settle for whatever discount percentage your current provider offers. Comparing quotes across multiple carriers typically reveals that different companies value these same discounts differently, sometimes creating 30 to 40 percent total savings when you stack bundling, safe driver status, and usage-based monitoring together. This combination approach transforms your premium from a fixed expense into something you can actively control.
The next step involves understanding how to actually apply these discounts to your specific situation-and that starts with knowing which bundle combinations work best for your household.
Building Your Best Bundle in Oregon
Why Bundling Delivers Real Savings
Most Oregon drivers treat their insurance policies as separate expenses, but this approach costs you hundreds annually. When you combine auto and home insurance under one carrier, you receive bundling auto and home insurance discounts that can range between 5 and 30 percent on your total premium. The real advantage emerges when you stack additional policies. Adding life insurance to an auto-home bundle typically produces another 5 to 10 percent reduction, while bundling business coverage alongside personal policies can reach 30 percent total savings. Insurers reward customer loyalty and reduce their administrative costs when managing multiple policies for one household.
How Different Carriers Value Bundle Discounts Differently
The challenge most people face is that different carriers value bundled coverage differently. One insurer might offer 22 percent off your auto premium for bundling home coverage, while another offers only 12 percent. This variance means comparing quotes across multiple carriers isn’t optional-it’s essential. When gathering quotes, ask each carrier for the specific discount percentage applied to each policy type and your total annual savings. Document these numbers side by side so you can see which carrier actually delivers the best outcome for your household’s specific situation.
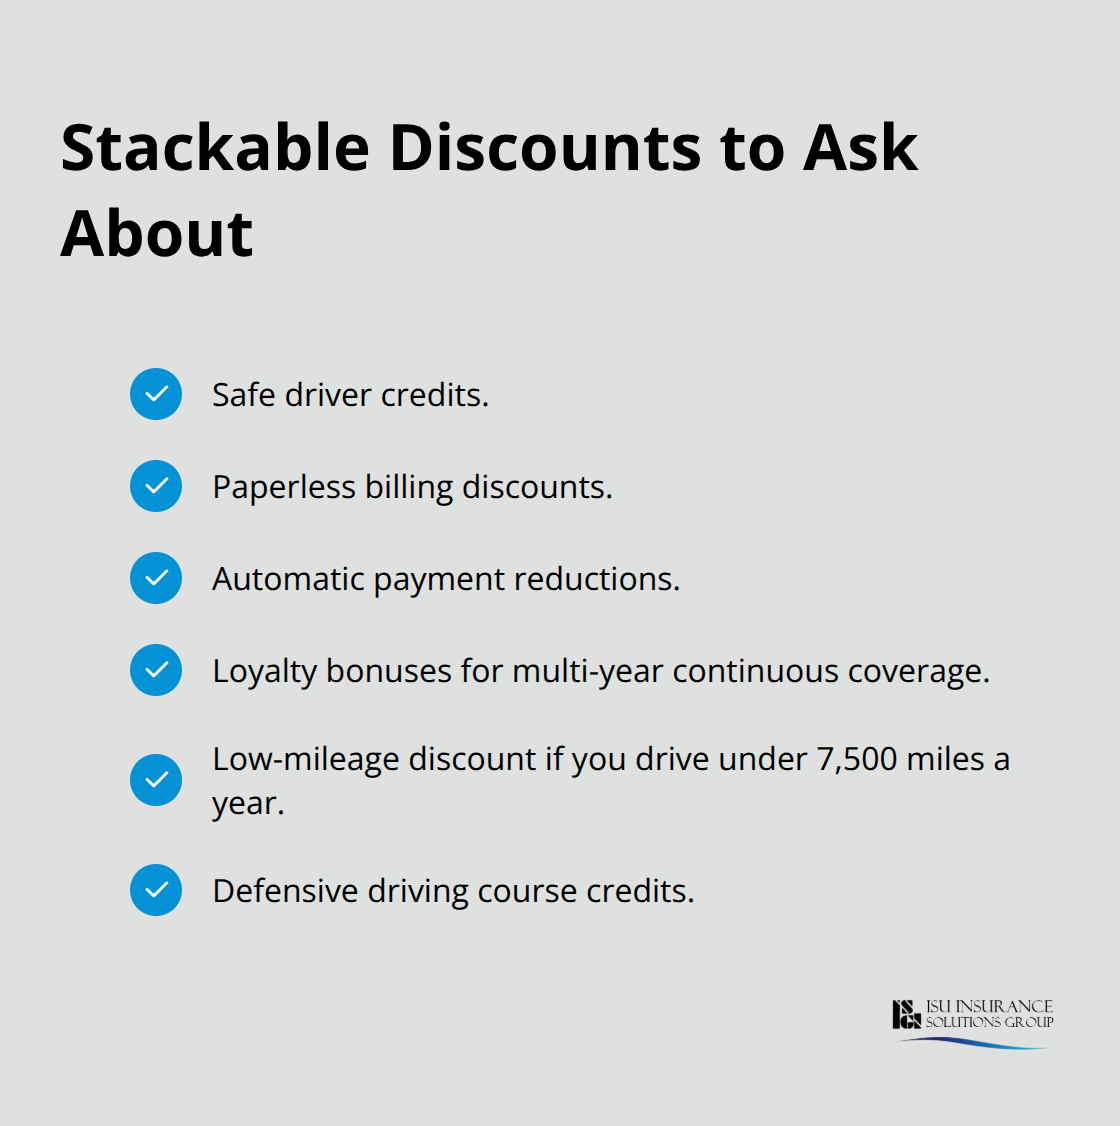
Some carriers front-load discounts on auto policies, others on home coverage. Your goal is finding the carrier whose discount structure matches your needs. Also request information about additional discounts that stack on top of bundling discounts (safe driver credits, paperless billing discounts, automatic payment reductions, and loyalty programs often combine with bundle discounts to produce even greater savings).
Comparing Quotes and Switching Carriers
Once you’ve identified your best option, confirm whether switching carriers involves any penalties with your current provider and whether the new carrier offers any additional incentives for new customers. The process requires effort upfront, but the annual savings justify the time investment. Multiple carriers operate in Oregon’s competitive insurance market, and each one structures their bundling discounts in ways that favor different customer profiles.
When you work with an independent agency, you gain access to quotes from multiple carriers simultaneously rather than contacting each company individually. This approach eliminates the tedious back-and-forth and produces a clear comparison of which bundle combination produces the lowest final premium for your specific household.
Stacking Additional Discounts with Your Bundle
Beyond bundling itself, you can stack multiple discount types to amplify your savings. Safe driver discounts, paperless billing credits, and automatic payment reductions all combine with your bundle discount to create compounding savings. Some carriers also offer loyalty bonuses for customers who maintain coverage for multiple years without gaps. These secondary discounts often get overlooked because people focus only on the primary bundle percentage, but they add meaningful reductions to your final premium.
The next step involves taking your bundled coverage and optimizing it further through safe driving programs that monitor your actual behavior on the road.
How Safe Driving Programs Lower Your Oregon Premium
Telematics Devices Track Your Actual Driving Behavior
Telematics devices represent the most direct path to premium reductions for drivers who actually drive safely. These apps or plug-in devices track your acceleration, braking patterns, speed consistency, and nighttime driving frequency, then translate that data into concrete discount percentages. Insurance companies using telematics programs report that participating drivers reduce their accident frequency by 15 to 20 percent according to research from the Highway Loss Data Institute. This isn’t theoretical-carriers base their discount structures on real claims data showing that monitored drivers genuinely cause fewer accidents.
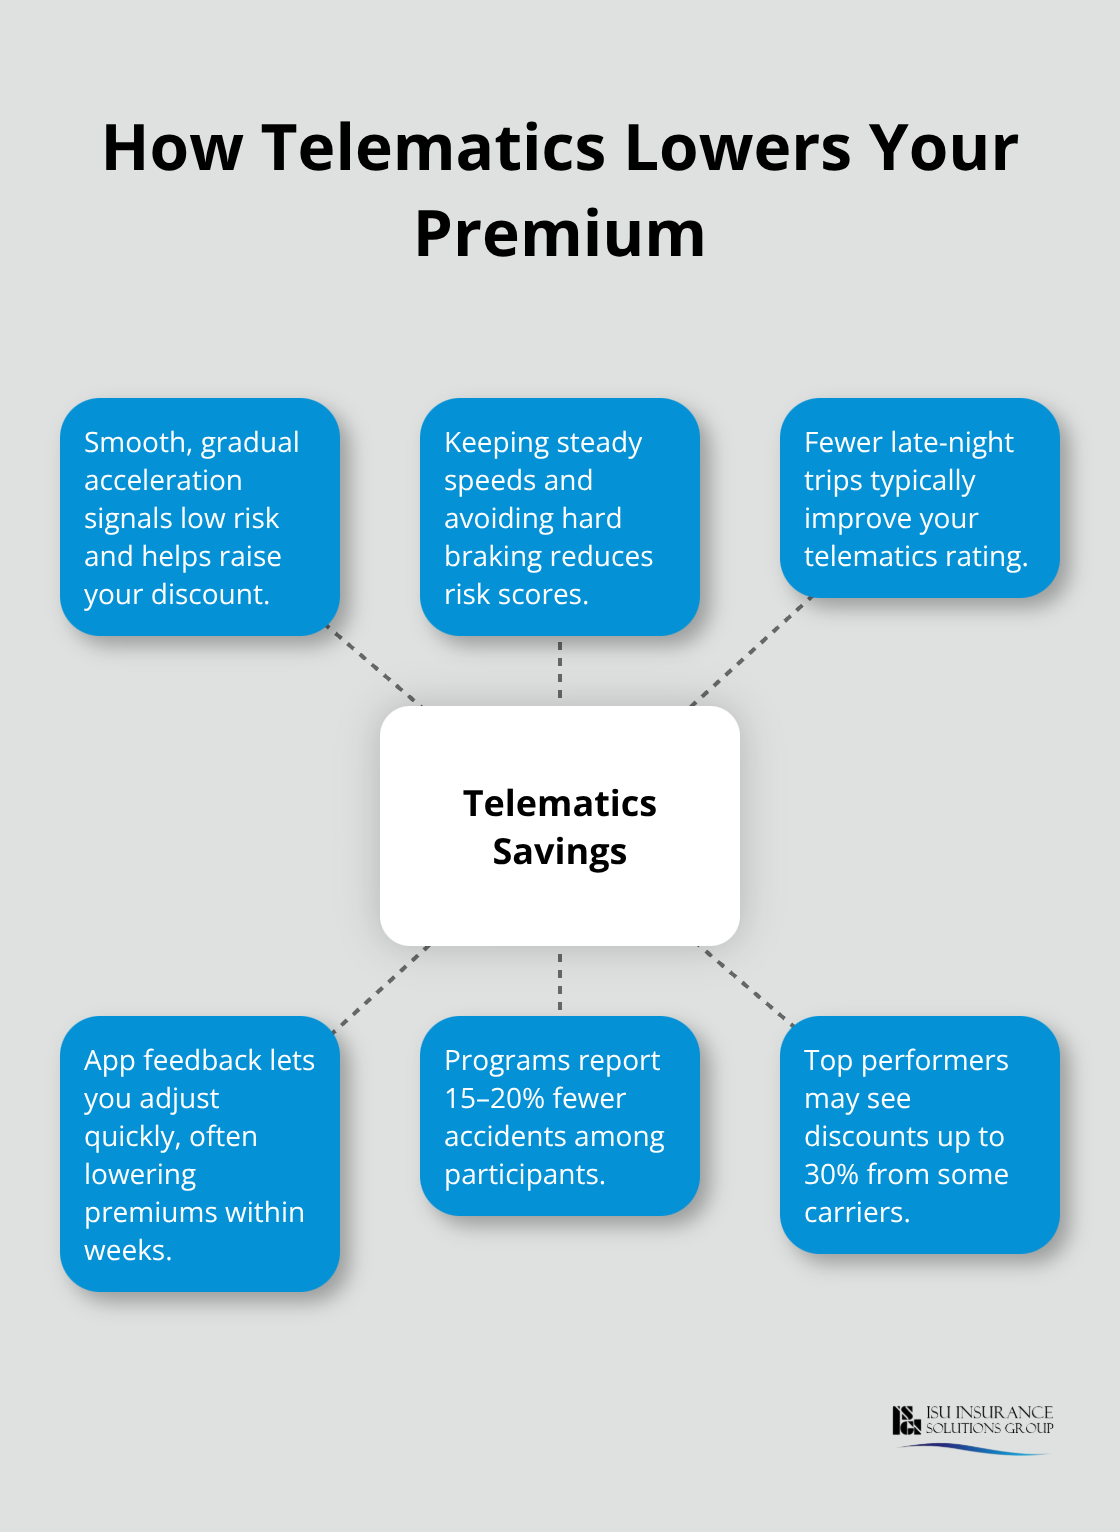
Oregon drivers who maintain consistent speeds, avoid hard braking, and limit nighttime driving can qualify for discounts reaching 30 percent. The key advantage: you control these discounts through your actual behavior rather than waiting years for an accident-free history to accumulate. Install the app, drive carefully, and your premium drops within weeks instead of months. Most carriers in Oregon’s market offer telematics programs, though the specific discount amounts and monitoring requirements vary significantly between providers.
Defensive Driving Courses Produce Fast Savings
Defensive driving course discounts operate differently but produce similar results. Completing a state-approved defensive driving course in Oregon typically qualifies you for a 5 to 10 percent discount that persists for three to five years. The National Safety Council and similar organizations offer online courses that take four to six hours to complete, costing between $20 and $50. This represents one of the fastest return-on-investment discounts available-you spend $40 and receive $100 to $200 in annual savings.
Accident-Free History Compounds Your Savings
Accident-free history discounts compound your savings even further. Safe drivers pay an average of 33% less for car insurance. Oregon drivers with three to five years without accidents or violations qualify for reductions depending on their insurer, and these discounts stack directly on top of your telematics and defensive driving credits. When you combine all three-a telematics discount of 25 percent, a defensive driving reduction of 8 percent, and an accident-free history credit-your total savings can reach 40 to 50 percent on your base premium.
Finding the Right Carrier for Your Driving Profile
The challenge most Oregon drivers face involves identifying which carriers reward which behaviors most generously. Different insurers structure their telematics programs, defensive driving credits, and accident-free discounts in ways that favor different driver profiles. One carrier might offer aggressive telematics rewards while another emphasizes accident-free history bonuses. Comparing these program structures across multiple carriers reveals exactly which insurer offers the highest actual discount for your specific driving profile. An independent agency can access quotes from multiple carriers simultaneously, eliminating the tedious process of contacting each company individually and producing a clear comparison of which combination produces the lowest final premium for your situation.
Final Thoughts
Oregon car insurance discounts represent real money in your pocket, but only if you actively pursue them. The three discount categories covered in this post-bundling policies, maintaining a clean driving record, and using telematics monitoring-work together to create substantial savings that compound over time. Most Oregon drivers leave hundreds of dollars on the table annually simply because they never compare their options or ask about available discounts.
Start by listing all your insurance policies across different carriers, then calculate what you’re currently paying for each one. Contact your existing providers and request a detailed breakdown of every discount you currently receive and every discount you qualify for but haven’t activated. This conversation often reveals overlooked savings opportunities that require nothing more than a phone call to implement, and it gives you a clear baseline for comparison.
Gather quotes from multiple carriers that show bundled rates, safe driver discounts, and telematics program options side by side-this comparison reveals which insurer actually delivers the lowest premium for your household rather than guessing based on marketing claims. ISU Insurance Solutions Group works with over 20 carriers throughout Oregon, which means one call produces quotes from multiple providers simultaneously rather than contacting each company individually. Our local agents understand Oregon’s specific insurance landscape and can identify which car insurance discounts Oregon drivers qualify for, eliminating the guesswork and producing concrete savings numbers you can act on immediately.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.





