
Independent Agent Insurance Washington: Getting Competitive Rates Without The Hassle
Most Washington residents overpay for insurance because they shop with direct insurers only. Independent agent insurance in Washington opens access to dozens of carriers and rates you won’t find online.
We at ISU Insurance Solutions Group know that working with an independent agent saves time and money. You get competitive quotes, personalized coverage, and support that direct insurers simply don’t provide.
Why Independent Agents Access Better Rates
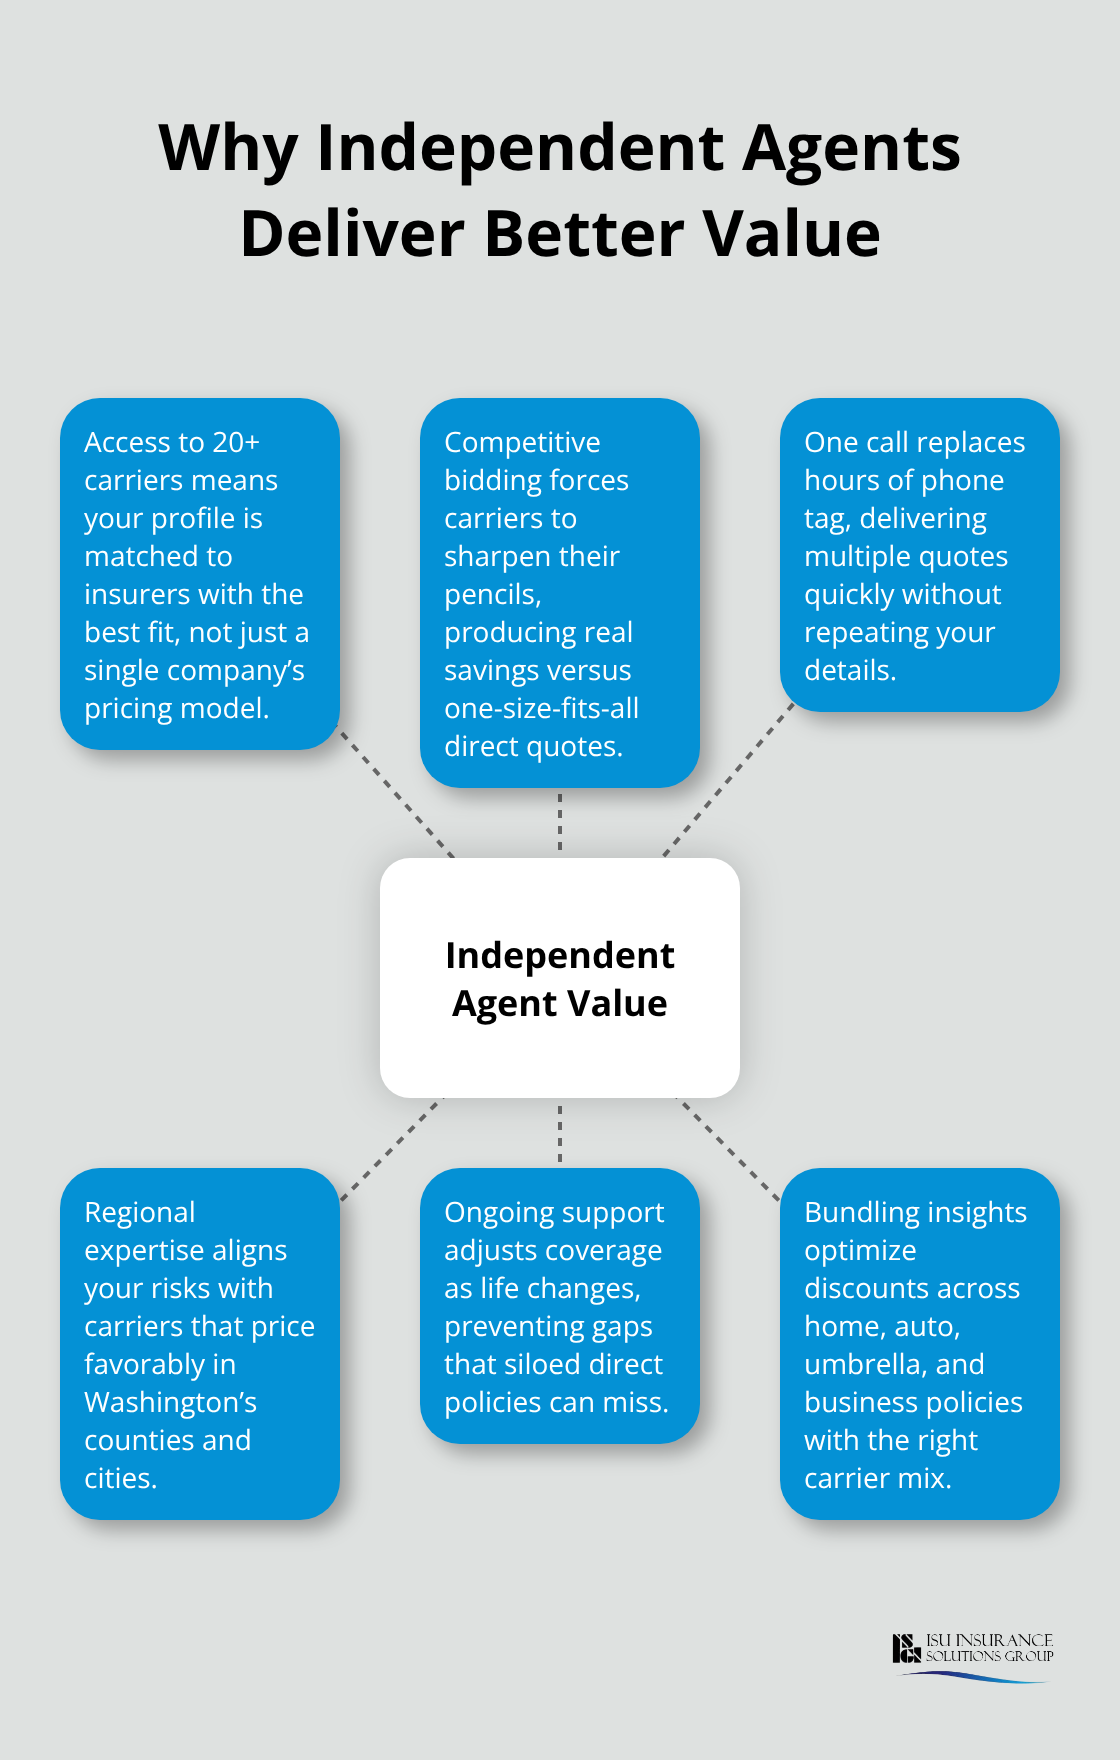
Independent agents in Washington tap into networks that direct insurers simply don’t have. We at ISU Insurance Solutions Group work with over 20 carriers, which means we pull quotes from companies that don’t sell directly to consumers. This isn’t a minor advantage-it’s the difference between paying standard rates and finding actual competitive pricing. Direct insurers like State Farm or Allstate operate on a single pricing model. They set their rates, and that’s what you pay. Independent agents operate differently. We shop your needs across multiple underwriters simultaneously, which forces carriers to compete for your business. The result is measurable savings. According to the National Association of Insurance Commissioners, consumers who shop with multiple carriers see significant savings on auto insurance. That’s real money staying in Washington residents’ pockets.
How carrier access translates to your rates
When you call a direct insurer, they quote you their rates based on their underwriting guidelines. When you call an independent agent, you receive quotes from carriers with different risk appetites, different discount structures, and different pricing philosophies. One carrier might price aggressively for homeowners with excellent credit but charge more for drivers with minor violations. Another carrier might do the opposite. Independent agents know these nuances and match them to your specific situation. A 35-year-old contractor in Seattle with a clean driving record but a home business might receive a quote of $2,400 annually with one carrier and $1,850 with another-both for identical coverage. That $550 difference exists because the second carrier values home-based business owners differently. Direct insurers can’t offer you that choice. They give you one quote and hope you don’t look elsewhere.
Local relationships that create better terms
Independent agents who’ve operated in Washington for decades build relationships with underwriters that matter. When a client needs coverage that sits outside standard guidelines (a contractor with a workers comp claim, a winery owner, someone with a non-standard driving situation), agents can often negotiate terms or access programs that online quotes never surface. These relationships also mean agents understand how each carrier prices in the Pacific Northwest specifically. Regional underwriting is real. A carrier might price aggressively in urban King County but conservatively in rural Spokane County. Independent agents know this. Direct insurers apply national pricing algorithms that miss these regional opportunities. Your location, your profession, your claims history-independent agents position these factors strategically across carriers who value them most favorably.
What makes the difference in Washington
The gap between independent agent rates and direct insurer rates widens when your situation becomes more complex. Standard profiles (young drivers, simple home coverage, clean records) see modest savings. Non-standard situations see dramatic ones. A contractor, a business owner, someone with a claims history-these profiles benefit most from an agent who knows which carriers welcome them and which ones don’t. This knowledge compounds over time. Agents who’ve worked in Washington since 1983 understand regional carrier preferences that no algorithm captures. They’ve negotiated with underwriters, learned their preferences, and built trust that translates into better terms for clients. That’s how independent agent insurance in Washington consistently delivers lower rates than direct shopping. This advantage becomes even more apparent when your coverage needs extend beyond basic auto and home policies.
How Independent Agents Get You Multiple Quotes Without the Runaround
One Call Replaces Hours of Phone Tag
Shopping for insurance the traditional way means calling State Farm, then Geico, then Progressive, then waiting on hold for each one. Independent agents compress that entire ordeal into a single conversation. An agent submits your information to 20+ carriers simultaneously, which means you receive competitive quotes without repeating your details five times or waiting days for callbacks. This isn’t a minor convenience-it fundamentally changes how quickly you can act on better rates.
A homeowner in Tacoma who discovers their current policy costs $200 more than available alternatives can switch within 48 hours instead of spending a week gathering quotes. The speed matters because rates change, and carriers adjust pricing based on seasonal demand and risk assessment updates. When you work with an independent agent, you don’t choose between speed and savings. You get both.
How Agents Actually Compete Carriers Against Each Other
The agent asks your situation once, then submits it to multiple underwriters with different risk appetites. You receive 5-8 quotes that actually differ because each carrier evaluates your profile differently. Direct insurers can’t replicate this. They give you their single quote and call it done.
One carrier might price aggressively for homeowners with excellent credit but charge more for drivers with minor violations. Another carrier might do the opposite. Independent agents know these nuances and match them to your specific situation. A 35-year-old contractor in Seattle with a clean driving record but a home business might receive a quote of $2,400 annually with one carrier and $1,850 with another-both for identical coverage. That $550 difference exists because the second carrier values home-based business owners differently.
Ongoing Support When Your Life Changes
The relationship doesn’t end once you buy a policy. Life changes-you add a vehicle, finish a home renovation, hire your first employee, or your teenager gets their license. With direct insurers, each change means another phone call, another wait, another quote that might be outdated. With an independent agent, you contact one person who understands your full coverage picture and adjusts everything in coordination.
A contractor in Seattle who adds a second work truck doesn’t just call about auto coverage; the agent reviews whether current liability limits still match the expanded operation, whether bundling options shifted with the new vehicle, and whether any carriers have released new discounts relevant to the updated profile. This comprehensive approach prevents coverage gaps that direct insurers miss because they compartmentalize policies.
Regional Knowledge That Shapes Your Rates
Independent agents who’ve operated in Washington for decades understand how regional factors affect not just initial quotes but ongoing adjustments. When your situation changes, that institutional knowledge means the agent doesn’t start from zero-they know which carriers reward certain changes and which ones don’t, allowing them to position your new circumstances strategically rather than just processing a transaction. A carrier might price aggressively in urban King County but conservatively in rural Spokane County. Independent agents know this. Direct insurers apply national pricing algorithms that miss these regional opportunities. This advantage becomes even more apparent when your coverage needs extend beyond basic auto and home policies, which is where independent agents reveal their true value in handling complex situations.
Common Mistakes That Cost Washington Residents Money on Insurance
Choosing Coverage Limits Without Professional Guidance
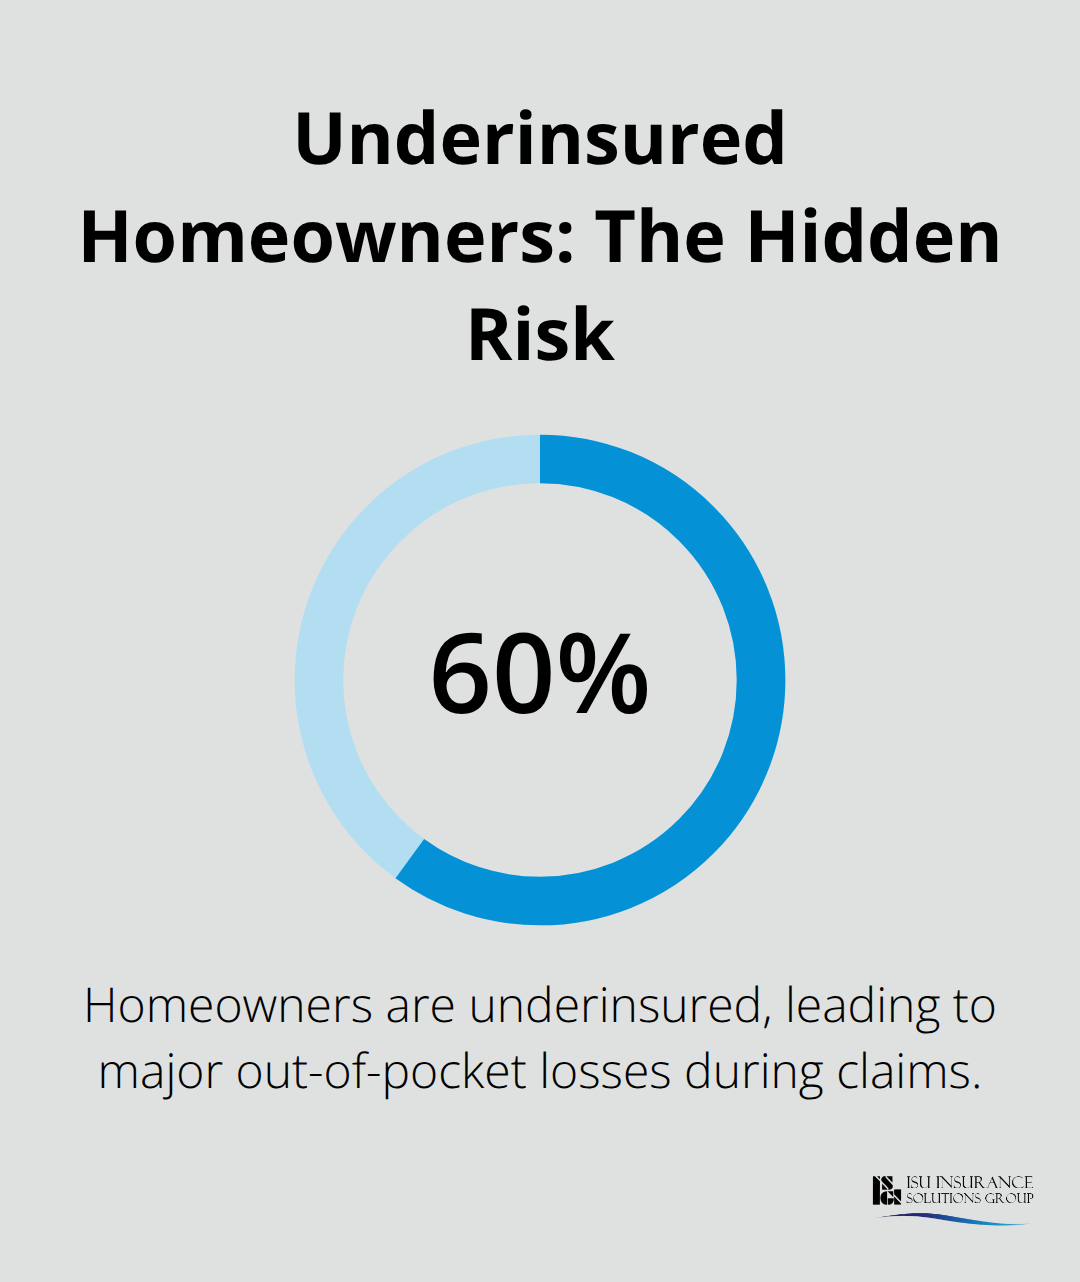
Most Washington residents choose coverage limits based on what feels affordable rather than what protects their actual assets. A homeowner with a $450,000 house picks $300,000 in dwelling coverage because the premium is lower, then discovers during a claim that underinsurance means the insurer applies a penalty. This isn’t rare-it’s the default mistake. The Insurance Information Institute reports that roughly 60% of homeowners are underinsured, which translates to thousands of dollars in uncompensated losses when damage occurs.
The problem worsens because direct insurers don’t challenge your choices. They quote the limits you request without context. An independent agent questions whether those limits actually match your situation. A contractor in Spokane with $200,000 in equipment and inventory might carry only $50,000 in business personal property coverage because nobody asked what he actually owned. When a job site fire destroys his tools, the gap becomes catastrophic.
Clients often discover massive shortfalls only when a claim arrives. The fix requires someone who understands not just your home value or business assets, but how insurance actually pays claims. Replacement cost versus actual cash value matters enormously. A roof that costs $18,000 to replace might pay only $12,000 under actual cash value, leaving a $6,000 gap that homeowners don’t anticipate. An independent agent walks through these distinctions and recommends limits based on what you’d actually need to rebuild or replace, not on what sounds reasonable.
Failing to Bundle Policies for Maximum Discounts
Bundling policies represents a major money leak for Washington residents. Those who buy auto insurance from one company, home from another, and skip business coverage entirely leave thousands on the table annually. Bundling discounts typically range from 10% to 25% across combined policies, but only if you consolidate with a single insurer. Direct insurers benefit from this fragmentation-each company captures what it can from you while you miss the full discount picture.
A Seattle homeowner paying $1,200 for home coverage and $900 for auto separately might pay $1,650 combined with a single carrier, saving $450 annually. But that math only works if someone calculates it. Most people don’t. Independent agents do this automatically. An agent reviews your entire coverage picture-home, auto, umbrella, business liability-and identifies which carrier combination maximizes discounts for your specific profile. Some carriers offer aggressive bundling discounts but weaker individual rates; others do the opposite. An agent knows which approach benefits you most.
Additionally, bundling creates operational efficiency that translates to better service. When everything sits with one agent, adjustments flow seamlessly. Add a vehicle, and the agent coordinates the auto addition with your home policy to confirm bundling still applies optimally.
Ignoring Annual Rate Reviews and Shopping Opportunities
Washington residents who don’t shop annually miss the reality that carrier pricing shifts constantly. A carrier might price aggressively this year and conservatively next year as their portfolio adjusts. The Insurance Journal found that roughly 40% of consumers who shopped for insurance received quotes at least 20% lower than their current premium.
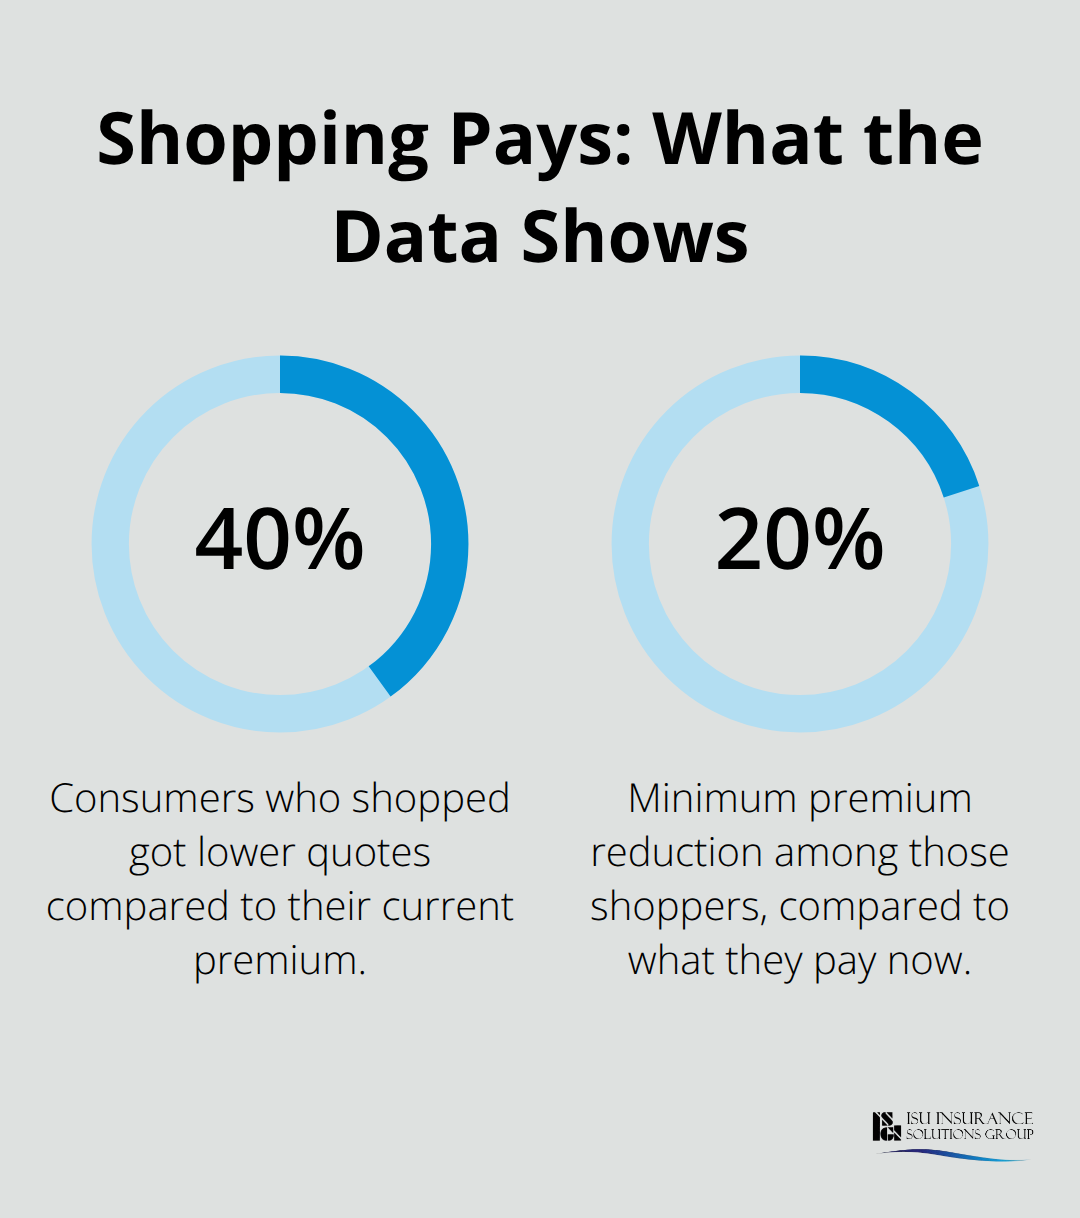
That gap exists because rates change, but only shopping reveals it.
Direct insurers have zero incentive to tell you that a competitor now prices better. Independent agents actively monitor rate movements and recommend shopping when opportunities emerge. A Bellevue resident insured for five years at $1,100 annually might discover that three carriers now quote $850 for identical coverage. Without an annual review, that difference multiplies across years into thousands in unnecessary premiums. The agent initiates this conversation; the direct insurer never does.
Final Thoughts
Independent agent insurance in Washington delivers competitive rates paired with personalized service that direct insurers simply cannot match. Multiple carriers competing for your business produces measurable savings, local expertise identifies opportunities that algorithms miss, and hands-on support prevents costly mistakes like underinsurance and missed bundling discounts. The real advantage compounds over time-a contractor who saves $600 in year one saves that amount again in year two, then year three, while a homeowner who bundles correctly protects both their premium and their actual assets.
We at ISU Insurance Solutions Group have served Washington and Oregon since 1983, working with 20+ carriers to deliver this value through one call that produces quotes from multiple underwriters simultaneously. Our agents understand Pacific Northwest risk profiles, regional pricing nuances, and which carriers welcome non-standard situations, whether you need auto, home, business, or specialty coverage like contractor liability or winery insurance. No phone tag, no repeated explanations, no waiting for callbacks that arrive too late to matter.
The gap between independent agent rates and direct insurer rates represents real money staying in your pocket. Connect with a local agent to start receiving better quotes today.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.





