
Restaurant Property Coverage: Guard Your Premises and Equipment
Your restaurant faces constant threats-from fires and theft to water damage and equipment loss. These risks can devastate your business financially and operationally.
Restaurant property coverage protects your building, equipment, inventory, and furnishings from these dangers. At ISU Insurance Solutions Group, we help restaurant owners understand what coverage they need and how to customize policies for their specific situation.
What’s Actually Covered Under Restaurant Property Insurance
Building Structure and Permanent Fixtures
Restaurant property coverage protects three distinct areas of your operation, and understanding what falls under each prevents gaps that could devastate your business. Your building structure includes the walls, roof, flooring, and permanent fixtures like built-in shelving or walk-in coolers. Interior components cover items permanently attached to the space: HVAC systems, electrical wiring, plumbing, and fire suppression systems. If you rent rather than own, this distinction matters significantly because landlords typically cover the building itself while you remain responsible for your tenant improvements.
Equipment, Furniture, and Operational Assets
Equipment and furniture protection covers the machinery that keeps your restaurant running-commercial ranges, fryers, ovens, refrigeration units, dishwashers, and point-of-sale systems. These items depreciate quickly, but a standard commercial property policy covers replacement cost or actual cash value depending on your policy structure. Furniture coverage includes dining tables, chairs, countertops, and shelving. Inventory and stock coverage protects your food, beverages, and supplies at their actual cash value. This matters because food waste represents a significant financial risk-a concern that deserves specific attention in your policy.
Matching Coverage Limits to Actual Replacement Costs
The real challenge isn’t understanding what’s covered theoretically; it’s matching your coverage limits to your actual replacement costs. A 2025 Next Insurance survey found that 38% of restaurant owners carried no business insurance at all, and many of those who did had inadequate property limits. You need to physically inventory your equipment and calculate replacement costs at current market prices, not what you paid five years ago.
A commercial fryer today costs $3,000 to $8,000 depending on capacity. A walk-in cooler runs $5,000 to $15,000. If your policy limit sits too low, you’ll face a coverage shortfall when losses occur.
Work with an agent to document your building square footage, construction type, and equipment specifications. Restaurants with alcohol service often need higher coverage limits due to increased liability exposure and premium costs. An independent agent can help you calculate accurate replacement values so your property coverage actually protects your investment when disaster strikes. Your next step involves identifying the specific risks your restaurant faces-from fire and theft to water damage-and understanding how property coverage responds to each threat.
Common Risks Facing Restaurants and How Coverage Protects You
Fire Damage in Commercial Kitchens
Fire remains the leading cause of property loss in commercial kitchens, and the damage extends far beyond flames. According to the National Fire Protection Association, cooking equipment is involved in roughly one-third of reported commercial kitchen fires. A single fryer fire spreads to ventilation systems and structural components within minutes, destroying equipment worth tens of thousands of dollars and forcing weeks of closure. Smoke damage penetrates walls, equipment, and inventory-contaminating food supplies that must be discarded entirely.
Property coverage pays for equipment replacement, structural repairs, and the cost to remove smoke-damaged inventory, but only if your policy limits match your actual replacement costs. Many restaurant owners underestimate equipment value and carry insufficient limits, leaving them exposed to catastrophic out-of-pocket expenses when fires occur.
Theft and Vandalism Losses
Theft and vandalism create different but equally damaging financial wounds. Restaurant locations with outdoor seating, delivery access, or high foot traffic face elevated theft risk from both external criminals and internal actors. A 2024 National Retail Federation survey found that organized retail crime cost businesses over $112 billion annually, with restaurants and bars experiencing significant losses from equipment theft, beverage inventory disappearance, and cash register breaches.
Vandalism targeting signage, windows, and exterior structures costs $2,000 to $10,000 per incident depending on damage severity. Property coverage reimburses these losses, but documentation matters critically-photographs, serial numbers, and purchase receipts accelerate claims processing and ensure you recover full replacement value rather than depreciated amounts.
Water Damage and Weather Events
Water damage and weather events create hidden financial exposure that many restaurant owners overlook until disaster strikes. Burst pipes, roof leaks, and failed HVAC condensation lines flood kitchens overnight, destroying equipment, ruining inventory, and forcing temporary closure. A single day of lost revenue for an average-sized restaurant exceeds $1,500 to $3,000 depending on sales volume.
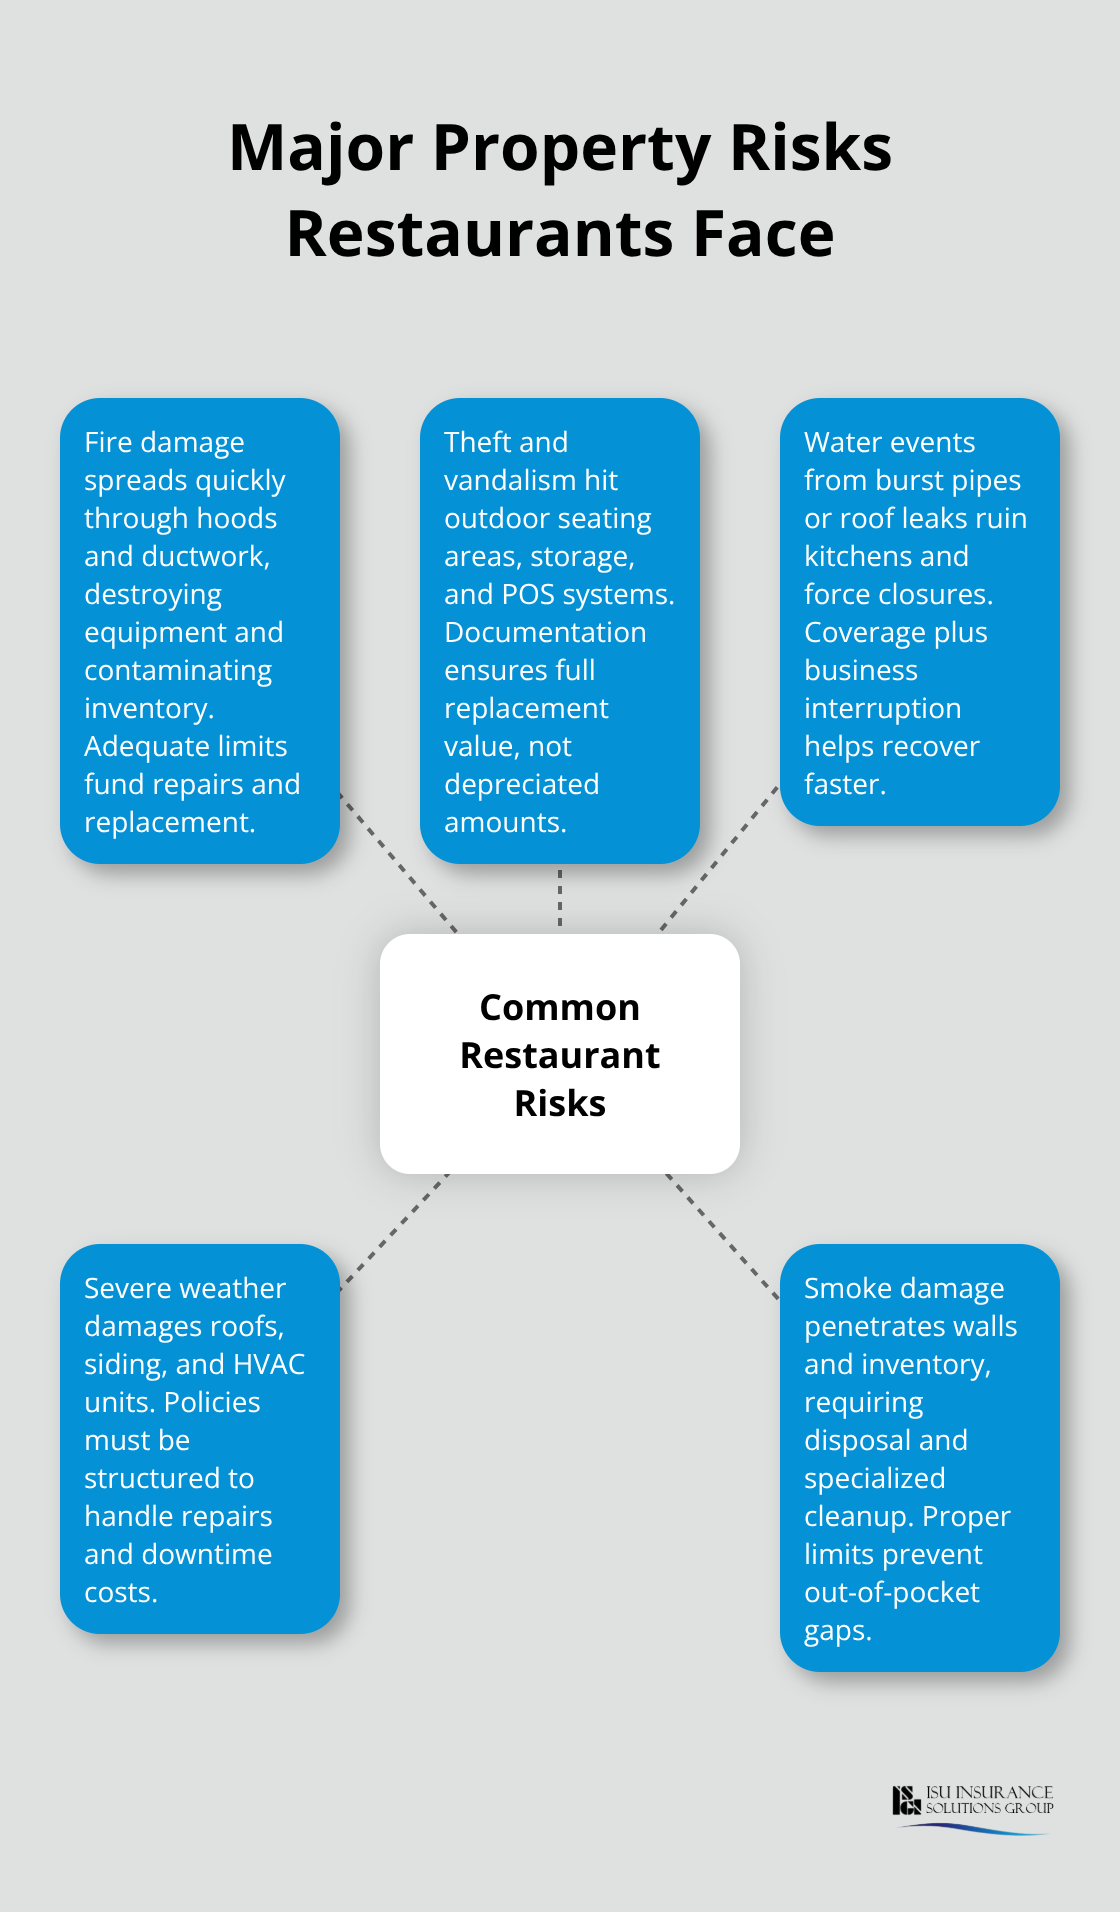
Seasonal weather-heavy rain, wind, hail, and snow-damages roofs, siding, and HVAC units that restaurant operations depend on constantly. Property coverage protects against these events, but the policy must include business interruption coverage to compensate for lost revenue and ongoing fixed costs during repairs. Without business interruption protection, you absorb all income losses while still paying rent, utilities, and payroll.
Protecting Your Investment Through Documentation
Documentation accelerates settlements and prevents disputes over pre-loss condition. Photograph your building exterior, equipment, and inventory annually so adjusters have clear baseline records if claims arise. This simple step transforms claim outcomes-adjusters process documented losses faster and settle for full replacement value rather than depreciated amounts.
Your property limits must reflect current replacement costs, not what you paid years ago. A commercial fryer today costs $3,000 to $8,000 depending on capacity. A walk-in cooler runs $5,000 to $15,000. Verify your coverage limits match these actual replacement prices so your policy protects your investment when disaster strikes. Understanding what your property coverage includes is only half the equation-the other half involves selecting the right coverage limits and customizing your policy to match your restaurant’s specific exposures.
How to Choose the Right Property Coverage for Your Restaurant
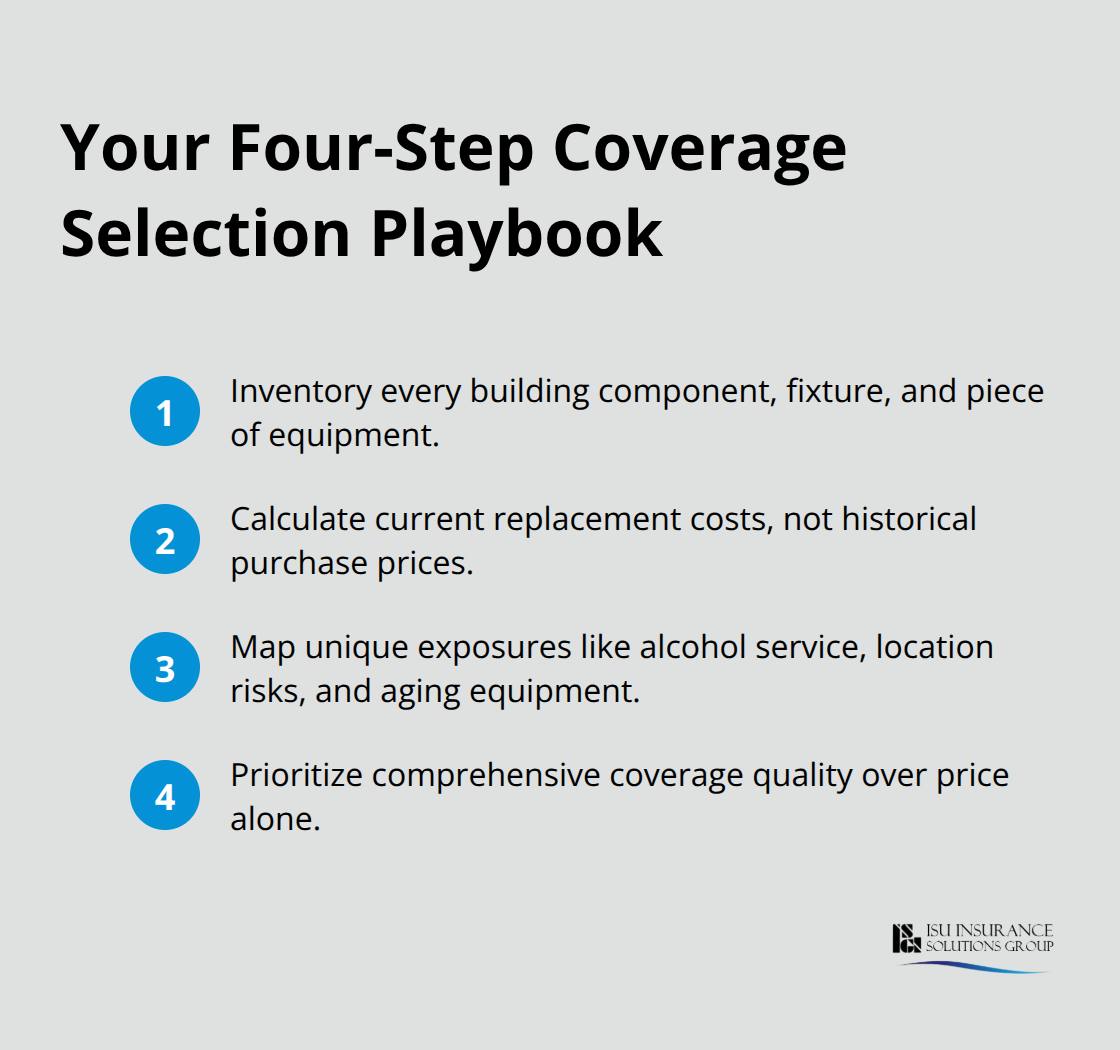
Start with a Physical Inventory of Your Building and Equipment
Walk through your restaurant with a notepad or spreadsheet and list every piece of equipment: ranges, fryers, ovens, refrigeration units, dishwashers, POS systems, furniture, and fixtures. Record the age, condition, and original purchase price for each item, then research current replacement costs online or contact vendors directly. A commercial six-burner range costs $4,000 to $6,000 new. A walk-in cooler runs $8,000 to $35,000. A hood suppression system can exceed $10,000.
These prices shift annually, so replacement cost today matters far more than what you paid three years ago. Measure your building square footage, note the construction type (wood frame versus masonry), and document permanent improvements like new flooring, HVAC upgrades, or kitchen renovations. This inventory becomes your foundation for setting accurate coverage limits-the single most important decision you make.
Match Coverage Limits to Actual Replacement Values
Many restaurant owners carry policies with limits 30 to 50 percent below actual replacement value, leaving themselves exposed to devastating out-of-pocket expenses when fires, theft, or water damage occur. The 2025 Next Insurance survey found that 38 percent of restaurant owners carried no business insurance at all, and many of those who did had inadequate limits that would leave them financially crippled by a major loss.
Your specific risk profile determines which additional coverages matter most. A restaurant with outdoor seating faces elevated theft and vandalism risk compared to a counter-service operation. A location near water or in a flood zone needs enhanced water damage protection and business interruption coverage to survive extended closure. A kitchen relying on aging equipment faces higher breakdown risk than one with recently replaced systems.
Assess Your Unique Risk Exposures
If you serve alcohol, your property coverage interacts with liquor liability exposure and may affect premium pricing. Document your annual revenue, number of employees, and whether you operate delivery services-these factors influence both coverage needs and premium costs. An independent agent can map these exposures systematically and recommend coverage that matches your operation rather than a generic restaurant package.
The agent reviews your building type, equipment inventory, loss history, and operational model to recommend appropriate coverage limits and endorsements. Request quotes from multiple carriers through one agent rather than shopping individual carriers separately-this approach gives you competitive pricing while maintaining consistent policy terms and local claims support.
Prioritize Coverage Quality Over Price Alone
Don’t select coverage based on premium alone; a cheaper quote with gaps creates false economy that evaporates the first time you face a major loss. Your property limits must reflect current replacement costs, not what you paid years ago. A commercial fryer today costs $3,000 to $8,000 depending on capacity. A walk-in cooler runs $5,000 to $35,000. Verify your coverage limits match these actual replacement prices so your policy protects your investment when disaster strikes.
Final Thoughts
Your restaurant property coverage protects your building, equipment, and inventory from fires, theft, water damage, and weather events that can devastate your operation financially. The 2025 Next Insurance survey found that 38 percent of restaurant owners carry no business insurance at all, and many who do have inadequate limits that won’t cover actual replacement costs. Your coverage limits must match what equipment costs today-a commercial fryer runs $3,000 to $8,000, and a walk-in cooler costs $5,000 to $35,000-not what you paid years ago.
Conduct a physical inventory of your building and equipment, calculate current replacement values, and match your policy limits to those figures. Document everything with photographs and serial numbers so claims move faster and settlements reflect full replacement value rather than depreciated amounts. Property coverage alone doesn’t complete your protection strategy; business interruption coverage compensates for lost revenue during repairs, and additional endorsements address specialized risks like equipment breakdown or spoilage from refrigeration failure.
Review your policy annually whenever your business changes, as equipment purchases, renovations, revenue growth, and operational shifts all affect your coverage needs. An independent agent can help you map these exposures and recommend appropriate limits and endorsements that match your restaurant’s unique risks. Contact ISU Insurance Solutions Group for a personalized quote that reflects your restaurant’s actual replacement values and protects your investment.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.





