
Brewery Property Insurance Washington: Protecting Your Taproom and Tanks
Running a brewery in Washington means managing risks that standard business insurance simply doesn’t cover. Fermentation tanks, specialized equipment, and on-site taproom operations create exposures that require brewery property insurance Washington specifically designed for your operation.
At ISU Insurance Solutions Group, we work with breweries across Washington to build protection plans that address production hazards, customer liability, and product-related claims. The right coverage keeps your business running when problems arise.
Why Standard Business Insurance Fails Breweries
Excluded Equipment Leaves You Exposed
Standard commercial property policies treat breweries like any other manufacturing operation, which creates immediate problems. A typical business policy excludes or severely limits coverage for fermentation tanks, glycol cooling systems, canning lines, and other equipment essential to your operation. When a glycol system fails-the single most costly claim type for Washington breweries-you face losses that easily reach six figures from spoilage, equipment repairs, and production downtime. Standard policies simply won’t cover this.
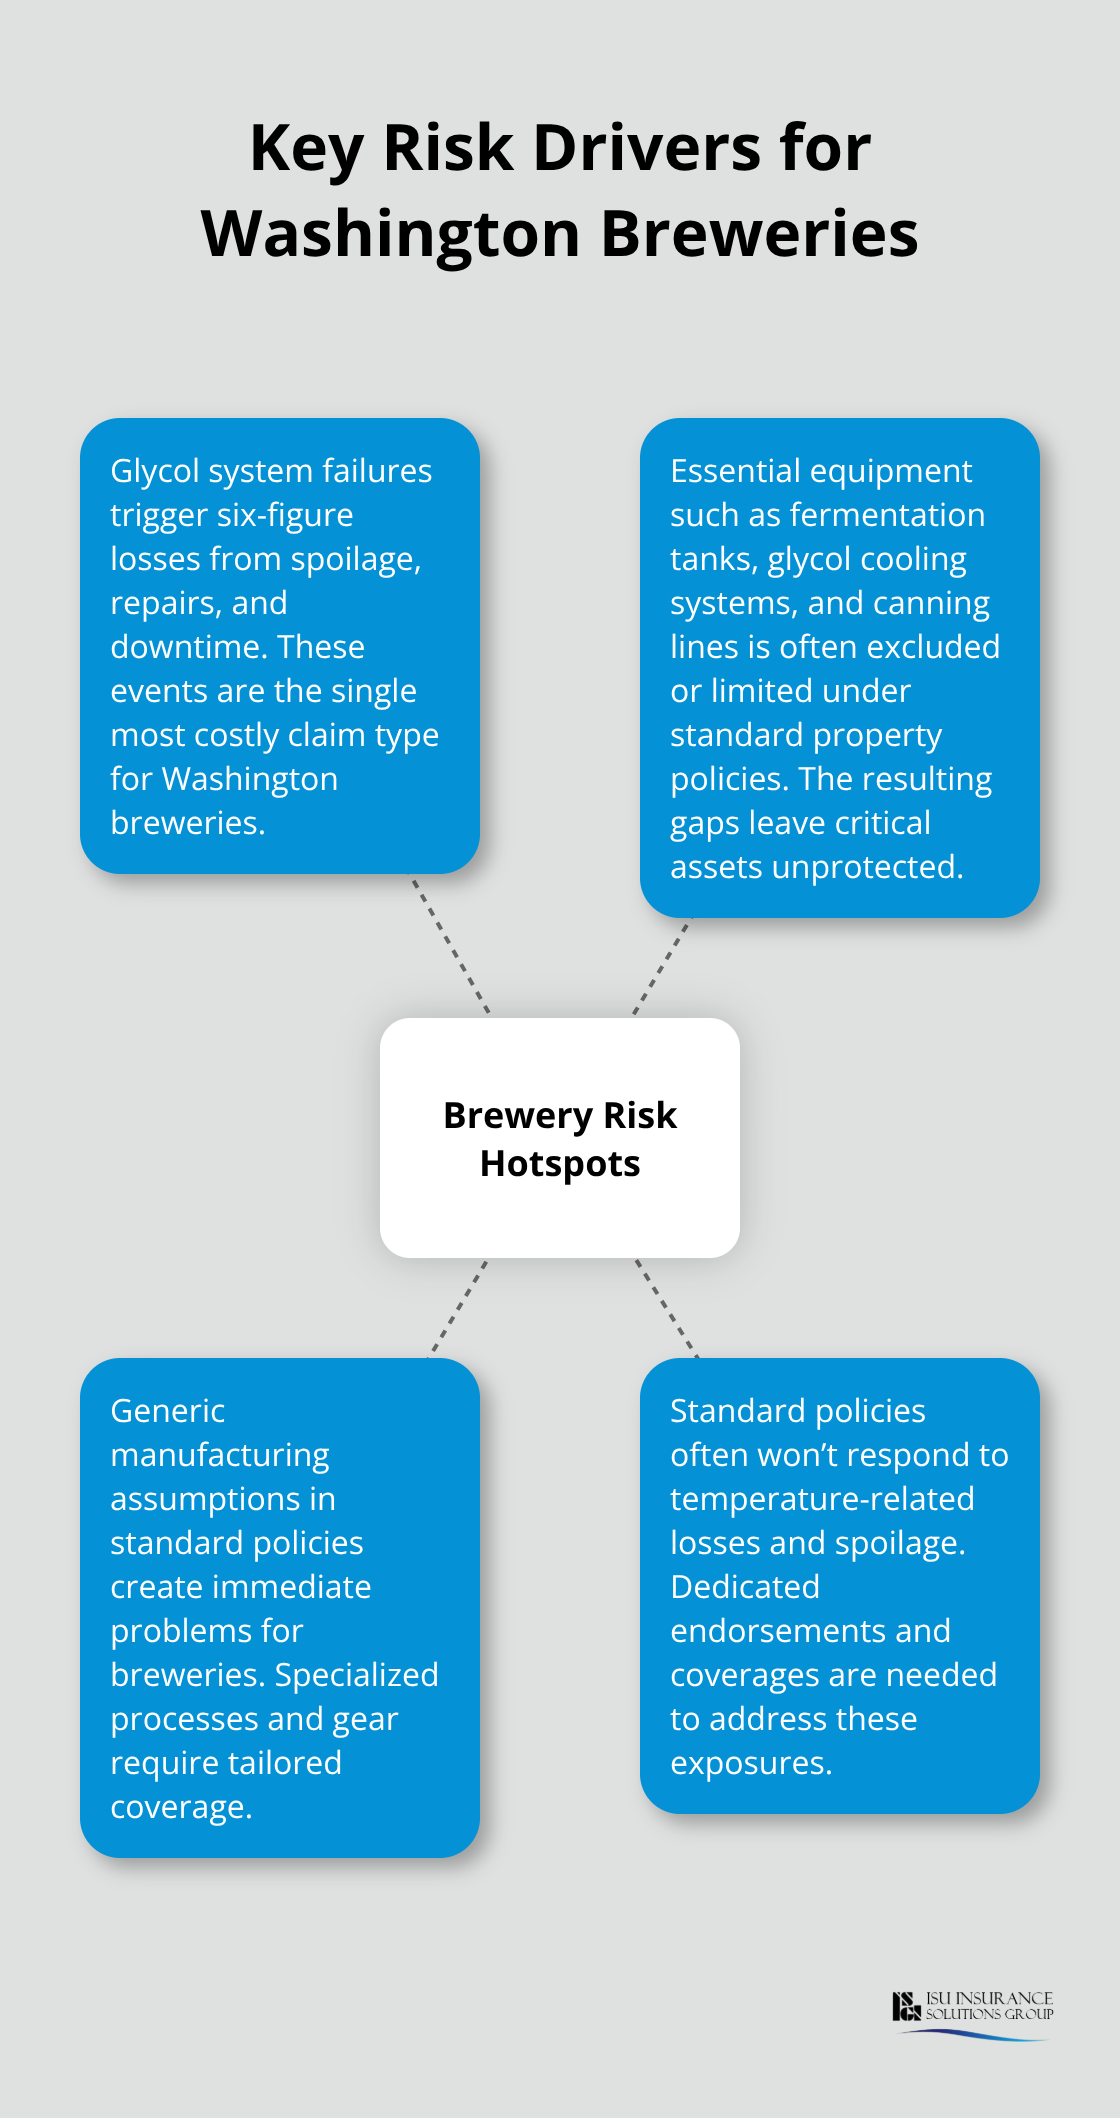
Washington has over 475 craft breweries according to the Brewers Association, and nearly every one has discovered coverage gaps the hard way after experiencing a loss.
Temperature Control Failures Destroy Inventory
Temperature control failures ruin entire fermentation batches, making spoilage coverage beyond standard property protection absolutely necessary to cover destroyed inventory and disposal costs. Replacement lead times for specialized brewery tanks and equipment exceed 26 weeks in many cases, which means robust business interruption coverage becomes critical to your survival during extended shutdowns. Your operation cannot wait months for new equipment to arrive while revenue stops flowing. Standard property policies ignore this reality entirely.
Taproom Operations Create Alcohol-Specific Liability
Your taproom operations add another layer of complexity that generic policies ignore. Standard general liability excludes alcohol-related incidents, but Washington’s dram-shop laws require you to carry liquor liability coverage as a licensing prerequisite with the Washington Liquor and Cannabis Board. You need at least one million dollars in commercial general liability plus mandatory liquor liability just to qualify for your license. If your facility exceeds 10,000 square feet, local fire marshals require documented proof of adequate property coverage and boiler coverage before you can operate.
Equipment Breakdown Demands Separate Protection
Brewing equipment breakdown coverage protects critical machinery like boilers, pressure vessels, and chillers as a separate layer from standard property. This coverage stands apart from your property insurance because it addresses sudden mechanical failures that property policies exclude. The distinction matters enormously when a chiller fails mid-fermentation or a canning line breaks down during peak production season.
An insurance provider with brewery experience understands these specific exposures and builds protection around your actual operation rather than forcing you into a generic mold. This expertise becomes your foundation for the coverage types that actually protect your business.
Coverage Your Brewery Actually Needs
Property Insurance Reflects Real Replacement Costs
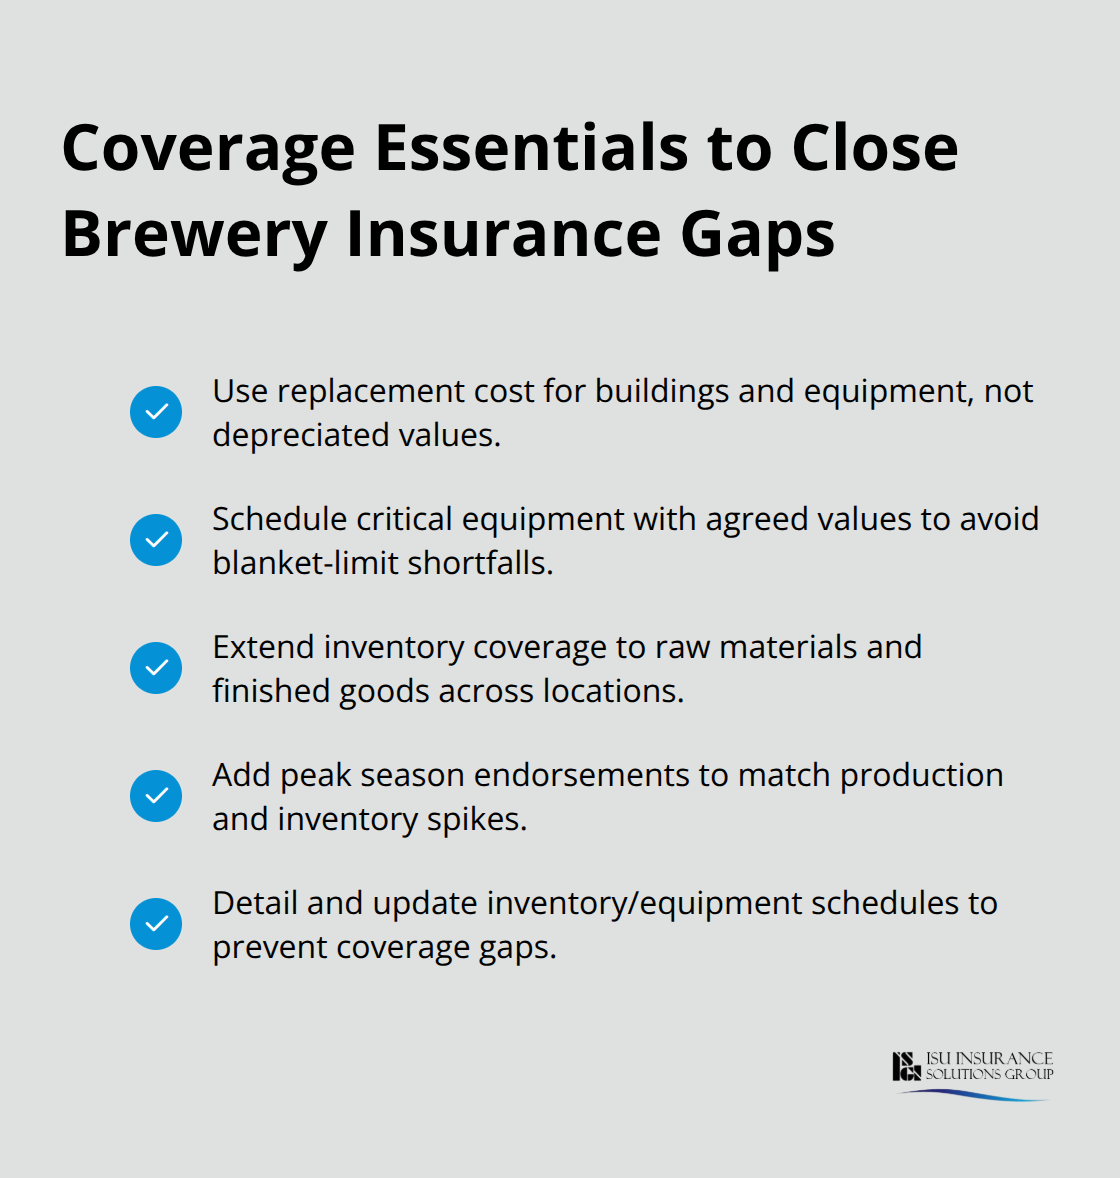
Property insurance forms the backbone of brewery protection in Washington, and it must reflect replacement cost rather than depreciated value. Seattle-area construction costs have risen approximately 20% since 2020, which means underestimating your building and equipment values leaves you dangerously exposed when rebuilding becomes necessary. Your policy needs to cover the concrete floors, temperature-controlled HVAC systems, and specialized tank placement that modern breweries require.
Scheduled Equipment Protection Prevents Coverage Gaps
Beyond the building itself, property coverage must protect scheduled equipment with agreed values rather than letting a standard policy apply blanket limits that fall short of actual replacement costs. Inventory coverage deserves equal attention-raw materials like hops, malt, and yeast fluctuate in value throughout the year, and finished beer stored across multiple warehouses and distribution channels requires detailed scheduling to prevent massive gaps when losses occur. Peak season endorsements automatically boost coverage limits during high-production periods when inventory values spike, preventing the underinsurance that catches many breweries off guard during their most profitable months.
Liability Coverage Addresses Different Exposures
General liability and product liability serve different purposes and demand separate attention. General liability protects against third-party bodily injury and property damage claims in your taproom and covers legal defense costs, but it specifically excludes alcohol-related incidents-a critical distinction that makes liquor liability mandatory as a separate policy under Washington law. Liquor liability coverage reimburses costs from contamination claims and mandated recalls when distributing across state lines, protecting your business when batches fail quality standards or face regulatory action.
Determining Adequate Coverage Limits
The Brewers Association reports Washington ranks fourth nationally for licensed breweries with over 475 operations, and facilities distributing statewide face genuine recall risk that generic policies ignore. Coverage limits should align with your annual gross sales for product liability, while general and liquor liability limits often need to reach 2–5 million dollars if you attend more than ten off-site festivals annually, sometimes requiring an umbrella policy to reach adequate protection without excessive individual policy costs. These limits protect your operation when claims arise, but selecting the right provider determines whether your coverage actually responds when you need it most.
How to Find a Brewery Insurance Partner That Actually Understands Your Operation
Ask Agents About Real Brewery Claims Experience
Generic insurance agents treat your brewery like a standard manufacturing facility, which is exactly why so many Washington breweries end up with massive coverage gaps after their first major loss. You need an agent who understands glycol system failures, fermentation chemistry, temperature-control risks, and the specific liability exposures that come with serving alcohol on-site. This expertise separates providers who can protect your operation from those who simply sell policies.
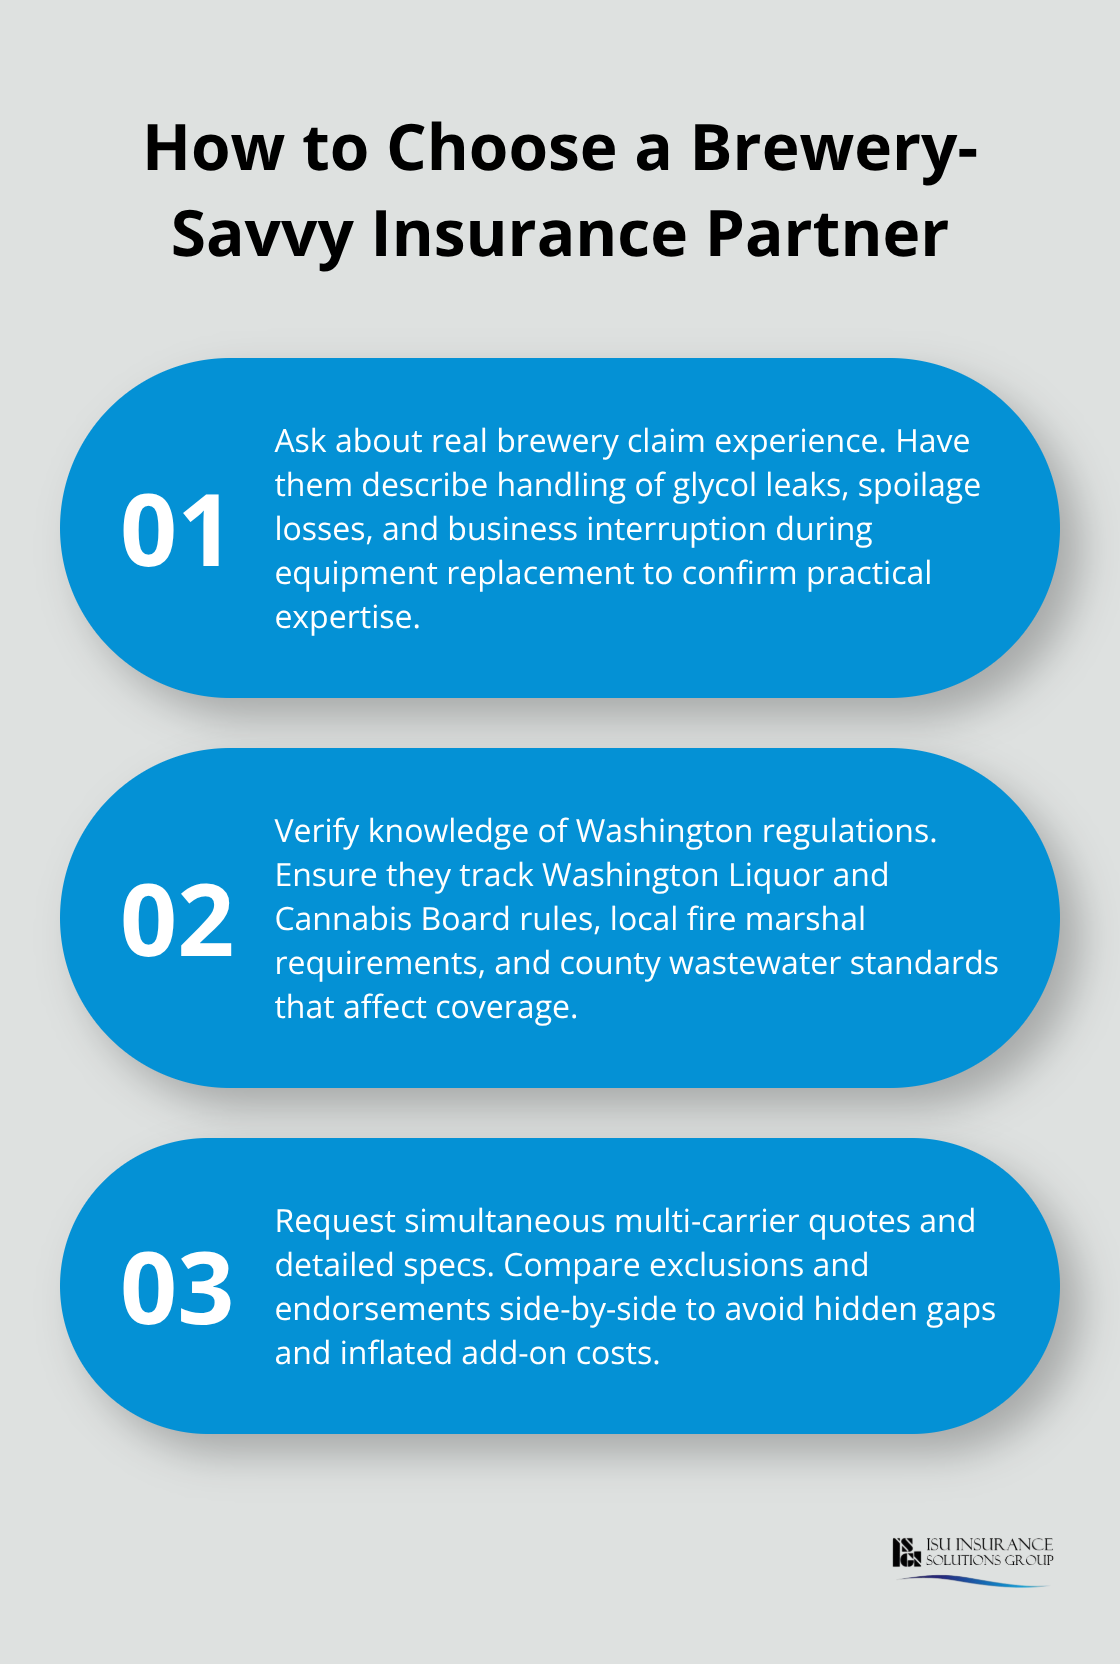
Start by asking potential agents whether they’ve handled brewery claims before-not general manufacturing claims, but actual fermentation equipment failures, spoilage losses, and dram-shop liability situations. An agent who can describe how they’ve resolved a glycol leak claim or managed business interruption coverage during equipment replacement knows the realities of your business. They’ll also understand why peak season endorsements matter when your inventory value spikes during summer production or why your equipment needs scheduled coverage rather than blanket limits.
Verify Knowledge of Washington Regulations
Confirm that agents maintain current knowledge of Washington Liquor and Cannabis Board requirements, local fire marshal regulations, and county-specific rules like Pierce County’s wastewater pollution-control standards that affect environmental liability coverage. These regulatory details change periodically, and an outdated agent misses critical compliance issues that create coverage exposure. An experienced brewery agent stays current with these shifting requirements and flags them during policy reviews.
Request Simultaneous Multi-Carrier Quotes
Obtaining quotes from multiple carriers reveals both competitive pricing and how different insurers value brewery risks. Request quotes simultaneously from at least three providers rather than shopping sequentially, which prevents carriers from adjusting their quotes based on competitor information. Specify your exact operation details: square footage, equipment lists with replacement costs, annual production volume, taproom hours, and number of off-site events annually. Vague requests generate vague quotes with hidden exclusions that appear only when you file a claim.
Compare What’s Excluded, Not Just What’s Included
When comparing quotes, focus on what’s excluded rather than what’s included-standard policies exclude glycol systems, spoilage coverage, and temperature-related losses unless specifically added. Calculate the true cost by adding all endorsements needed to match your actual risks, not just the base premium. A cheaper base policy that requires expensive add-ons often costs more than a higher premium that includes comprehensive coverage.
Verify each quote includes separate liquor liability limits meeting your Washington license requirements and confirm property coverage reflects current replacement costs rather than depreciated values based on 2020 pricing. An independent agency serving Washington with deep Pacific Northwest expertise and access to multiple carriers can provide one-call multi-carrier quotes that let you compare offerings without shopping individually, which saves time and surfaces competitive options quickly.
Final Thoughts
Protecting your Washington brewery demands coverage that extends far beyond standard business insurance. Property insurance reflecting current replacement costs, equipment breakdown protection for critical machinery, liquor liability meeting state licensing requirements, and product liability covering contamination or recall situations form your essential foundation. Your operation faces unique risks from glycol system failures, temperature-control losses, and alcohol-service liability that generic policies simply ignore, making brewery property insurance Washington specifically designed around your actual operation non-negotiable.
Local expertise identifies coverage gaps that national carriers miss entirely. An agent familiar with Washington Liquor and Cannabis Board requirements, local fire marshal regulations, and Pacific Northwest brewery claims patterns understands why peak season endorsements prevent underinsurance during your highest-revenue months and why scheduled equipment coverage protects your fermentation tanks and canning lines better than blanket limits. This knowledge translates directly into policies that respond when you need them most.
Request multi-carrier quotes from an independent agency with deep Pacific Northwest experience and access to multiple carriers serving breweries. ISU Insurance Solutions Group has served Washington and Oregon since 1983 with specialty expertise in brewery coverage, offering one-call multi-carrier quotes and hands-on local agents who understand your operation. Contact them to compare offerings, verify coverage limits match your actual risks, and secure the protection your taproom and tanks deserve.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.





